Your £500,000 house doesn’t make you financially secure; it might be masking a serious cash flow problem that puts your retirement at risk.
- True financial health is measured by ‘liquid solvency’—the accessible cash and investments you have—not by illiquid ‘paper wealth’ tied up in your property.
- High property equity cannot pay monthly bills, cover unexpected expenses, or solve a sudden loss of income, creating a dangerous ‘house-rich, cash-poor’ trap.
Recommendation: Shift your financial strategy from simply growing your total net worth to actively increasing your liquid assets while methodically reducing high-interest debt. This is the key to building genuine, stress-free financial resilience for your pre-retirement years.
As an independent financial advisor, I frequently meet pre-retirees across the UK in a similar position: on paper, they are millionaires, thanks to decades of property price growth. Yet, behind the scenes, they are grappling with significant anxiety. They feel ‘house-rich, but cash-poor,’ stressed by outstanding mortgage payments, car finance, and credit card balances. The conventional wisdom tells them to simply calculate their net worth by subtracting liabilities from assets. But this approach is dangerously flawed, as it equates the locked-in value of your home with the cash you need to live on.
This common calculation creates a false sense of security. It fails to distinguish between ‘paper wealth’ and the ‘real wealth’ that provides genuine financial freedom and resilience. The real risk isn’t a drop in your property’s value; it’s a disruption to your income when your wealth is not accessible. Relying on your home as your primary financial safety net is like owning a gold bar in the desert when what you truly need is a bottle of water.
But what if the key to financial security wasn’t about your total net worth, but about your ‘liquid solvency’? What if you could measure your financial health based on what you can actually access and deploy, rather than an abstract figure tied to the property market? This is the shift in mindset required to build a truly robust financial future. This guide will provide you with a new framework, used by finance professionals, to calculate your true financial position accurately and implement strategies to improve it, ensuring your retirement is built on a foundation of liquid security, not illiquid hope.
To navigate this crucial financial transition, this article breaks down the essential components for assessing and improving your real-world wealth. We will explore the vital distinction between different asset types and provide actionable strategies to strengthen your financial standing as you approach retirement.
Summary: A Practical Guide to Real-World Asset and Liability Management
- Liquid Wealth vs Tied Assets: What Actually Counts Towards Your Net Worth?
- The Danger of Relying Solely on Your Primary Residence for Future Solvency
- How to Eradicate £10,000 of Unsecured Debt While Maintaining Your Savings?
- Why a £500,000 House Does Not Save You From Monthly Insolvency Risks?
- At What Exact Age Should Your Liquid Assets Finally Exceed Your Total Debts?
- How to Calculate Your Debt-to-Income Ratio Exactly Like a UK Bank Underwriter?
- Overpaying Your Mortgage vs Index Funds: Where Should You Put Your Extra Cash?
- How to Maximize Tax-Free Compounding Inside Your Stocks and Shares ISA?
Liquid Wealth vs Tied Assets: What Actually Counts Towards Your Net Worth?
The first step towards genuine financial clarity is to stop thinking about ‘net worth’ and start focusing on ‘liquid net worth’. Your total net worth is a vanity metric; your liquid net worth is your survival metric. It represents the resources you can access quickly to cover expenses without having to sell assets at a loss. A common mistake is lumping all assets together. For instance, a person with £116,000 in assets and £112,000 in liabilities might seem stable, but if most of those assets are illiquid, their real buffer is closer to a mere £4,000. This is the solvency gap—the difference between perceived wealth and actual, accessible cash.
So, what counts? Liquid assets are the cornerstone of your real wealth. These include:
- Cash in your current and savings accounts.
- Money held in money market funds.
- Investments in your Stocks and Shares ISA or General Investment Account that can be sold and settled within a few days.
In contrast, tied or illiquid assets include your primary residence, investment properties, private company shares, and sometimes even pensions with withdrawal restrictions. While valuable, converting them to cash involves significant ‘financial friction’—estate agent fees, legal costs, capital gains tax, and time. You cannot use a brick from your house to pay for your weekly shop at Tesco.
Calculating your liquid net worth is straightforward: sum up all your liquid assets and subtract all your liabilities (mortgage, loans, credit cards). This number, not your total net worth, is the true measure of your ability to withstand financial shocks. It’s the metric that determines if you can handle a boiler breakdown or a period of unemployment without spiralling into further debt. Many individuals with a high total net worth discover their liquid net worth is alarmingly low, or even negative, a clear signal that their financial strategy needs an urgent reset.
The Danger of Relying Solely on Your Primary Residence for Future Solvency
For many in the UK, the family home is not just a place to live; it’s seen as the primary retirement fund. This mindset is the single greatest threat to financial security for pre-retirees. Being ‘house-rich and cash-poor’ is a state of extreme financial fragility. Your property’s value is theoretical until the day you sell it, yet your mortgage and other debt repayments are very real monthly demands on your cash flow. This mismatch between an illiquid asset and liquid liabilities is a recipe for stress and potential disaster.
This illustration below powerfully captures the paradox: a substantial, valuable asset that, instead of providing security, casts a shadow over your day-to-day financial reality.
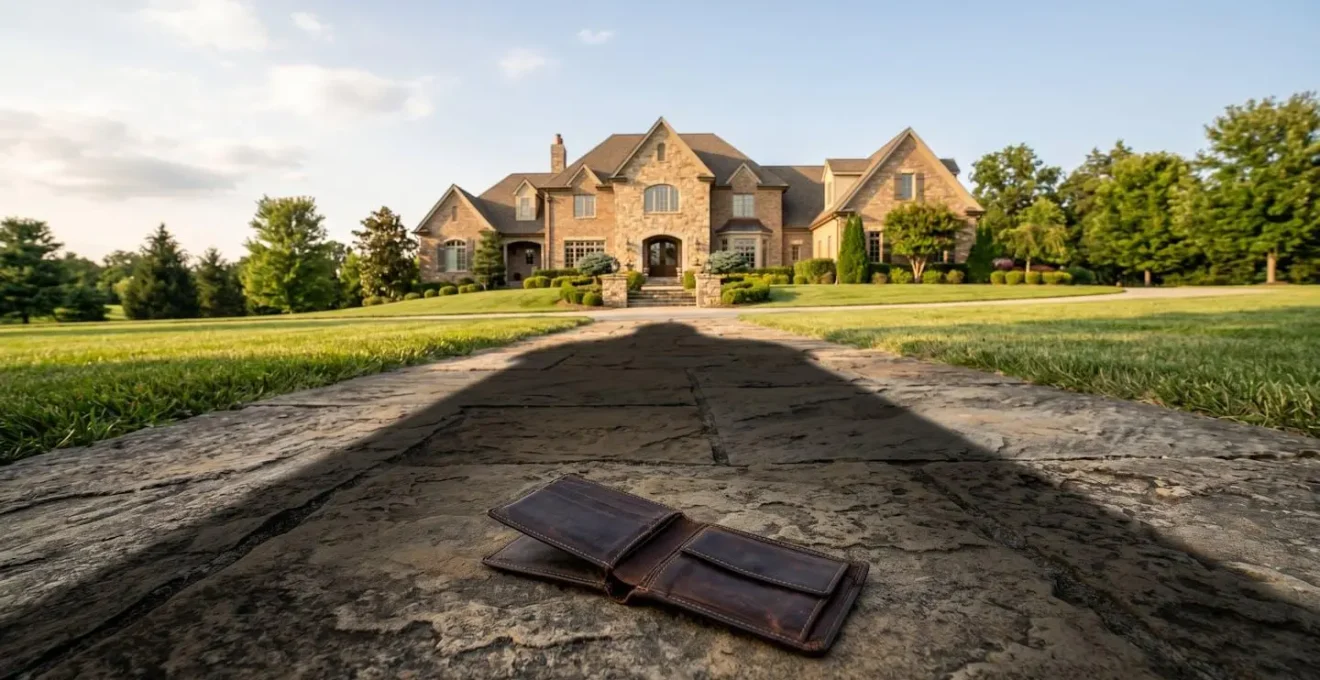
As the image shows, owning a high-value property doesn’t automatically translate to financial stability. If your income stops, you cannot use your home’s equity to pay your bills without taking on more debt (like an equity release or another loan), which only increases your monthly outgoings and exacerbates the problem. For those approaching retirement, the goal should be to reduce financial obligations, not add to them. As a benchmark, Financial Samurai’s retirement analysis shows that a 10:1 asset-to-liability ratio or higher is ideal for individuals in their 60s. Crucially, a growing proportion of those assets must be liquid to provide genuine solvency.
Relying on downsizing in the future is also a risky strategy. It assumes you will be able to sell at the right time, for the right price, and that you will find a suitable, cheaper property to move into. It leaves your entire retirement plan at the mercy of the property market and personal circumstances. A far safer approach is to build a portfolio of liquid assets that runs parallel to your property wealth, giving you flexibility, control, and peace of mind.
How to Eradicate £10,000 of Unsecured Debt While Maintaining Your Savings
For those feeling the squeeze of monthly debt payments, the instinct might be to halt all savings and throw every spare pound at the debt. This is often a mistake. Wiping out your emergency fund to clear a credit card leaves you completely exposed to the next financial shock, forcing you back into debt. The smarter strategy is a dual-pronged approach: attack high-interest debt aggressively while simultaneously building up your liquid savings buffer. The key is to allocate your resources based on the « cost » of your debt.
Not all debt is created equal. High-interest unsecured debt (credit cards, personal loans) is a financial emergency that actively destroys your wealth. Low-interest debt, like a mortgage, is more manageable. The following decision matrix provides a clear framework for prioritising your extra cash, based on a similar model used by financial professionals.
| Interest Rate on Debt | Emergency Fund Status | Recommended Action |
|---|---|---|
| Above 15% APR | 3 months expenses saved | Prioritise debt payoff (70% debt/30% savings) |
| 8-15% APR | 3-6 months saved | Balanced approach (50/50 split) |
| Below 8% APR | 6+ months saved | Focus on savings/investing (30% debt/70% savings) |
To put this into practice, you can adopt a ‘dual-goal’ strategy. First, calculate your ‘psychological safety number’—the minimum cash reserve you need to sleep at night (typically 1-3 months of essential expenses). Focus on reaching this number first. Once achieved, you can implement the allocation strategy. List all your debts by interest rate and channel the majority of your efforts towards the most expensive one (the ‘avalanche method’). A common, effective split is allocating 60-70% of your extra monthly income to the highest-rate debt and the remaining 30-40% to your savings until you have a robust 3-6 month emergency fund. This method ensures you are making progress on both fronts: reducing financial drag and increasing your liquid solvency.
Why a £500,000 House Does Not Save You From Monthly Insolvency Risks
It’s a dangerously common misconception: « I have £300,000 of equity in my house, so I’m fine. » This thinking completely ignores the concept of cash flow. Insolvency doesn’t happen because you lack assets; it happens because you lack the cash to meet your monthly obligations. A high-value property is irrelevant when the council tax bill arrives or the car finance payment is due. Financial ratios that look only at total assets versus total liabilities are misleading. For instance, while BDC’s financial analysis reveals that a 30% debt-to-asset ratio is considered low risk from a balance-sheet perspective, this static number says nothing about your ability to service that debt month-to-month.
The true risk is liquidity. When faced with a sudden income loss—due to redundancy, illness, or a business downturn—a homeowner’s first thought is often to « use the equity. » But how? The most common tool, a Home Equity Line of Credit (HELOC) or a further advance on your mortgage, is a trap. It involves taking on more debt to solve a cash flow problem. This action directly increases your monthly outgoings at the precise moment you can least afford it, accelerating you towards insolvency rather than away from it.
Case Study: The Home Equity Trap
Consider a homeowner with a £500,000 property and an outstanding mortgage of £100,000. They have £400,000 in equity but only £10,000 in savings. When they are made redundant, they take out a £30,000 equity loan to cover living expenses. Their debt has now increased to £130,000, and they have an additional monthly loan payment on top of their mortgage. Their liquid savings are gone, their monthly breakeven point is higher, and they are now in a more precarious financial position than before, despite their significant home equity.
This scenario demonstrates that property equity is not a substitute for an emergency fund. It is a slow, expensive, and often counter-productive source of liquidity in a crisis. The only true defence against monthly insolvency risk is a sufficiently large fund of liquid assets, completely separate from your property, that can be deployed instantly with no fees or further obligations.
At What Exact Age Should Your Liquid Assets Finally Exceed Your Total Debts?
For anyone serious about a secure retirement, there is a magical moment to aim for: the ‘Crossover Point’. This is the age at which your accessible, liquid financial assets (cash, ISAs, investments) officially become greater than your total outstanding debts (mortgage, loans, etc.). Reaching this milestone signifies a fundamental shift in your financial position. You move from a state of being a net debtor, reliant on future income or selling assets to cover liabilities, to a state of true liquid solvency. You are no longer working to pay off the past; your assets are now working to secure your future.
While some aggressive early retirement strategies aim for this crossover early on—for instance, a Financial Samurai case study demonstrates a 3:1 asset-to-liability ratio as a minimum for retiring at 34—the goal for a pre-retiree is different. It’s less about aggressive growth and more about de-risking. The aim should be to hit this crossover point at least 5-10 years before your planned retirement date. This provides a crucial buffer period where your liquid wealth can compound without the drag of significant debt, and it gives you immense psychological security. Knowing you could, in theory, write a cheque to clear all your debts is a powerful position to be in.
Calculating your personal crossover age isn’t guesswork; it’s a projection based on your current situation and future actions. By systematically tracking your progress, you can turn an abstract goal into a tangible, achievable target.
Your Plan to Reach the Crossover Point
- Establish Your Baseline: Document your current liquid assets (cash, ISAs, investments) and total debts (mortgage, loans) with precise figures. This is your starting line.
- Calculate Your Savings Rate: Determine the exact percentage of your net income that you save or invest each month. This is the engine of your wealth growth.
- Project Your ‘Wealth Velocity’: Your goal is for your liquid assets to grow faster than your debts. Target a ‘wealth velocity’ where your net asset growth (savings rate + investment returns) is at least 4% higher than the average interest rate on your debts.
- Factor in Major Milestones: Account for known future lump-sum expenses or windfalls, such as children’s university fees, inheritance, or final mortgage payments. Adjust your projection accordingly.
- Identify Your Crossover Year: Using a simple spreadsheet, project the growth of your liquid assets and the reduction of your debts year by year. The year they cross is your target. Adjust your savings rate to bring this date forward.
How to Calculate Your Debt-to-Income Ratio Exactly Like a UK Bank Underwriter
When you apply for a mortgage or loan, lenders don’t just look at your assets. A far more critical metric for them is your Debt-to-Income (DTI) ratio. This figure tells them what percentage of your gross monthly income is already committed to servicing existing debt. It’s a direct measure of your monthly cash flow pressure and your ability to take on new payments. With UK household debt averaging a staggering 133.8% of disposable income in recent years, lenders are scrutinising this figure more closely than ever. Knowing how to calculate it yourself, exactly as they do, gives you a powerful insight into your own financial health and borrowing capacity.
Bank underwriters in the UK follow a specific, conservative methodology. They don’t just use your basic salary; they stress-test your finances to see if you could cope with changing circumstances. Here is their step-by-step process:
- Calculate Gross Monthly Income: This includes your basic salary plus an average of any regular bonuses or commission you’ve received over the last two years.
- Apply a ‘Haircut’ to Variable Income: Underwriters are cautious. They will typically discount any non-guaranteed income, like freelance earnings or irregular overtime, by 25-50% to simulate a bad year.
- Sum ALL Monthly Debt Payments: This is comprehensive. It must include your mortgage/rent, personal loans, car finance, student loans, and the minimum monthly payments on all your credit and store cards.
- Stress-Test Variable Debts: For any debts with a variable interest rate (like tracker mortgages or some loans), they will often add 1-2% to the current rate to see if you could still afford the payments if rates were to rise.
- Calculate the Ratio: They divide your total stressed monthly debt payments by your discounted gross monthly income and multiply by 100. A DTI of 20-30% is seen as low-risk, 30-45% is manageable, and anything over 45% is a major red flag that often leads to a decline.
However, a high DTI isn’t always an automatic ‘no’. UK mortgage brokers note that underwriters can show flexibility with compensating factors. An applicant with a DTI over 50% might still be approved if they have a large deposit, a credit score over 750, or have maintained the same job for over five years. Some specialist lenders even assess applications more holistically, without a strict DTI ceiling. Understanding this calculation is the first step to managing your liabilities effectively.
Overpaying Your Mortgage vs Index Funds: Where Should You Put Your Extra Cash?
This is the ultimate strategic dilemma for homeowners with spare cash: should you pay down your mortgage faster for a guaranteed ‘return’ equal to your mortgage interest rate, or should you invest in the stock market for potentially higher, but non-guaranteed, returns? The answer, as with most financial questions, is: it depends. The optimal choice hinges on three factors: your mortgage interest rate, your expected investment return, and, most importantly, your time horizon to retirement and personal risk tolerance.
Overpaying your mortgage offers a guaranteed, tax-free return. If your mortgage rate is 4%, every pound you overpay is effectively earning you 4%, risk-free. This is particularly appealing in a high-interest-rate environment or for those who are risk-averse and value the certainty of being debt-free sooner. Investing in a Stocks and Shares ISA, on the other hand, offers the potential for much higher returns through exposure to global stock markets, but comes with volatility and risk. The following matrix offers a simplified guide for this decision.
| Years to Retirement | Mortgage Rate | Expected Market Return | Optimal Strategy |
|---|---|---|---|
| 20+ years | 3-4% | 7-8% | 80% index funds, 20% mortgage overpayment |
| 10-20 years | 4-5% | 6-7% | 50/50 balanced approach |
| Under 10 years | 5%+ | 5-6% | 70% mortgage overpayment for guaranteed return |
For pre-retirees with less than 10-15 years until they stop working, the argument for prioritising mortgage overpayments becomes much stronger. The primary goal at this stage is de-risking. A guaranteed 5% return from clearing your mortgage is often more valuable than chasing a volatile 7% in the market when you have less time to recover from a downturn. A hybrid strategy can also be effective: build up an ‘overpayment reserve’ in a flexible cash or low-risk investment account. During market highs, let it grow; during market downturns, you can deploy it to pay down mortgage principal, providing both flexibility and security.
Key Takeaways
- Your financial security depends on your ‘liquid net worth’ (accessible cash and investments), not your total net worth which is inflated by illiquid property.
- Relying on your home for retirement is a high-risk strategy; focus on building a parallel portfolio of liquid assets like a Stocks and Shares ISA.
- Adopt a dual-pronged strategy: methodically pay down high-interest debt while consistently building your emergency savings to increase true solvency.
How to Maximize Tax-Free Compounding Inside Your Stocks and Shares ISA
Once you have a handle on your debts and a clear picture of your liquid solvency, the most powerful tool for building real wealth in the UK is the Stocks and Shares ISA. It is the ultimate vehicle for achieving your ‘Crossover Point’. An ISA allows you to invest up to £20,000 per tax year, with all returns—whether from capital gains or dividends—being completely free of tax. This tax-free status supercharges the effect of compounding over time, but only if you manage it correctly.
The single biggest enemy to compounding is fees. Even seemingly small charges can have a devastating impact on your long-term returns. As a stark example, investment platform analysis demonstrates that a 1% annual management fee can consume nearly 30% of your potential returns over a 30-year period. Therefore, the first rule of maximising your ISA is to ruthlessly minimise costs by choosing low-cost index funds or ETFs, ideally with an ongoing charge figure (OCF) below 0.2%.
Beyond minimising costs, a strategic approach to what you hold inside your ISA can make a significant difference. This is known as ‘asset location’. The goal is to shelter your highest-growth potential assets from tax, maximising the benefit of the ISA wrapper.
- Place high-growth assets inside the ISA: This includes individual stocks, small-cap funds, or emerging market trackers that have the highest potential for capital gains.
- Enable automatic dividend reinvestment: This is the engine of compounding. Ensure any dividends paid out are automatically used to buy more shares of the fund, creating a virtuous cycle of growth.
- Use your full allowance early: Invest your £20,000 allowance as early as possible in the tax year (which starts on April 6th) to give your money the maximum amount of time to grow in the market.
- Rebalance annually without tax fears: An ISA allows you to sell investments that have grown significantly and reinvest in others to maintain your desired asset allocation, all without triggering a Capital Gains Tax bill.
By treating your ISA not as a simple savings account but as a strategic compounding machine, you can dramatically accelerate the growth of your liquid wealth. This is the final and most crucial step in building a financial future that is not just theoretically wealthy on paper, but practically and comfortably secure in reality.
To put these principles into practice, the logical next step is to conduct a thorough audit of your own finances, calculate your true liquid solvency, and create a concrete plan to improve it. Start today by taking control of your financial future.