The common wisdom that you must trade significant equity for growth capital is a dangerous myth for UK founders.
- Early-stage funding should be sequenced, starting with non-dilutive government loans and cash flow optimisation before considering equity.
- Giving away equity to an angel or VC too soon severely devalues your future exit and can lead to a loss of strategic control.
Recommendation: Master the art of strategic funding by layering different capital sources, using equity as the final, most expensive option, not the first.
For ambitious UK founders, the moment arrives when your profitable business is straining at the seams, ready for national expansion. The immediate, reflexive thought is often a binary choice: take on a bank loan or find an investor. This is the first, and most critical, strategic error. The landscape of business funding is presented as a simple menu, but in reality, it’s a complex chessboard. The common advice to « find an angel investor » or « go for venture capital » often omits the brutal truth about equity dilution and loss of control, a truth I saw play out countless times from the other side of the table as a venture capitalist.
The real key to scaling successfully isn’t just finding money; it’s about architecting a funding sequence. It’s about understanding which type of capital is right for which stage of growth, and how to access cheaper, non-dilutive options first to build value before you even consider selling a piece of your company. This is about protecting your most valuable asset: your future exit value and your autonomy as a founder. Most articles will give you a list of options; this guide will give you a strategic playbook.
This article will deconstruct the most common funding pathways for UK SMEs, moving beyond the surface-level pros and cons. We will analyse the true cost of angel investment, detail how to secure government-backed loans, compare the real-world impact of VC versus crowdfunding, and identify the precise financial and operational triggers that should guide your funding decisions. It’s time to stop thinking like someone asking for money, and start thinking like a capitalist deploying it strategically in your own business.
This guide provides a strategic roadmap for UK founders, outlining how to finance growth while maintaining maximum control. Explore the detailed analysis of each funding option to build a capital strategy that serves your long-term vision.
Summary: The Founder’s Playbook for Strategic UK SME Funding
- Why Handing 20% of Your Startup to an Angel Investor Ruins Your Future Exit Value?
- How to Secure a £25,000 Government Start Up Loan to Fund Your First Employee?
- Venture Capital vs Equity Crowdfunding: Which Drives Faster Customer Acquisition?
- The Premature Scaling Mistake That Bankrupts 70% of Seed-Funded Startups
- When Exactly Should You Transition Your Profitable Side-Hustle Into a Limited Company?
- How to Force Large Corporate Clients to Accept 15-Day Payment Terms?
- How to Legally Separate Your Personal Savings From Your UK Business Liabilities?
- How to Leverage Your Property Equity to Fund High-Growth Business Ventures?
Why Handing 20% of Your Startup to an Angel Investor Ruins Your Future Exit Value?
The allure of an angel investor is powerful: a seasoned expert provides a significant cash injection and invaluable advice. The seemingly standard request for 15-20% of your company can feel like a fair price for this opportunity. This is a cognitive trap. What is rarely modelled by first-time founders is the cascading effect of this initial dilution. This isn’t a one-time transaction; it’s the first domino in a series that can systematically dismantle your personal wealth at exit. An early, large equity give-away sets a precedent and a valuation ceiling that makes future funding rounds more difficult and more dilutive.
The British Business Bank notes that typical angel investments in the UK involve the investor taking between 10% and 25% of the equity. Let’s be clear: that 25% represents a quarter of your entire life’s work, handed over at the point of maximum risk and lowest valuation. When a Series A investor comes along later, they see a « messy » cap table with a founder who is already significantly diluted and potentially less incentivised. This reduces their interest and forces you to accept a lower valuation in the next round, triggering even more dilution to raise the same amount of capital. It’s a vicious cycle that starts with that first « friendly » angel check.
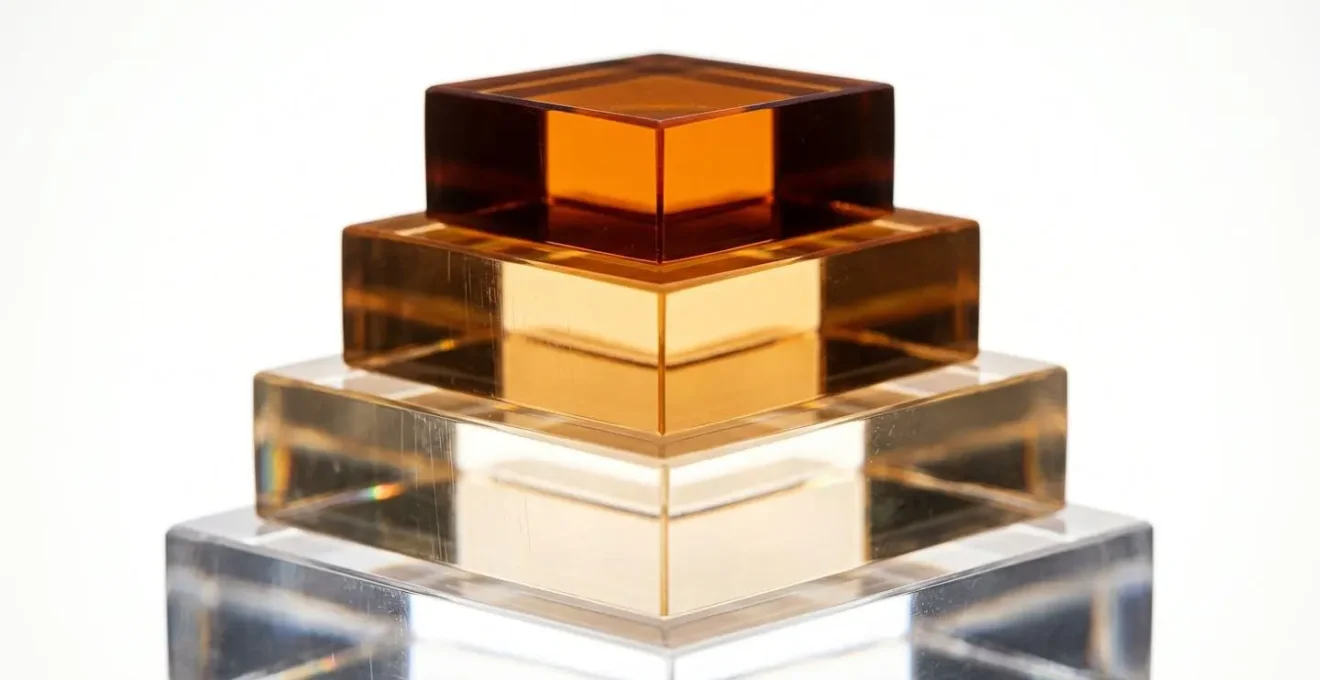
This visual representation of layered dilution is crucial to understand. Every round of funding adds a new layer, and each new layer shrinks the relative size of your own. The strategic mistake is not in taking investment, but in taking it too early and giving away too much when non-dilutive options are still on the table. A founder’s primary goal should be to build as much enterprise value as possible *before* selling equity. By handing over a large stake at the seed stage, you are selling your future potential at a steep discount, a decision that can cost you millions upon exit.
How to Secure a £25,000 Government Start Up Loan to Fund Your First Employee?
Before you even think about an angel’s chequebook, your first port of call for funding a specific growth milestone, like a first hire, should be the UK Government’s Start Up Loan scheme. This is arguably the most founder-friendly debt available. It is an unsecured personal loan for business purposes, meaning you don’t need assets or a long trading history. More importantly, it is non-dilutive. You retain 100% of your equity while securing the capital needed to generate more revenue.
The scheme, administered by the British Business Bank-owned Start Up Loans Company, provides funding from £500 to £25,000 at a fixed 7.5% annual interest rate. For a founder looking to hire a junior salesperson or a digital marketer, £25,000 is often enough to cover salary and initial costs for 6-9 months – a critical window to prove that the new role can generate a return on investment. The key to a successful application is not just having a good idea, but demonstrating in a detailed cash flow forecast precisely how that new employee will generate enough revenue to service the loan repayments and contribute to net profit within a 12-month period. It’s a test of your operational planning as much as your vision. Remember, this is a personal loan, so a check on your personal credit history is part of the process.
Securing this loan is a critical step in the strategic funding sequence. It allows you to professionalise your operation and increase your revenue-generating capacity without surrendering any ownership. When you do eventually approach equity investors, you are no longer a sole trader with an idea; you are a director of a growing business with employees and a proven ability to manage debt and generate returns. This fundamentally changes the power dynamic in your favour.
Your Action Plan: Pre-application Checklist for UK Start Up Loan Success
- Verify eligibility: Confirm your business has been trading for less than 60 months and you have the right to work in the UK.
- Prepare a detailed business plan demonstrating how the employee will generate revenue to cover their salary and loan repayments within 12 months.
- Create a comprehensive cash flow forecast showing loan repayment capability over the 1-5 year term.
- Identify your preferred Delivery Partner (e.g., Virgin StartUp, Transmit Startups) and review their specific application criteria.
- Ensure personal credit history is in order, as this is an unsecured personal loan requiring a credit check.
- Prepare supporting documents including financial projections, market validation evidence, and proof of personal financial commitment.
Venture Capital vs Equity Crowdfunding: Which Drives Faster Customer Acquisition?
When your business is ready for a significant equity injection to fuel rapid customer acquisition, the choice often boils down to two paths: the traditional Venture Capital (VC) route or the more modern Equity Crowdfunding (ECF) model. The common perception is that VCs bring « smart money » and strategic connections, while ECF is simply a way to raise capital from the public. This overlooks the fundamental difference in how each model impacts your primary growth driver: acquiring customers.
VCs, especially in the B2B space, can be incredibly effective. Their value is in leveraging their network. A partner at a top-tier VC firm can make an introduction to a key executive at a FTSE 100 company, potentially shortening a sales cycle from 18 months to three. This is their superpower: providing warm leads and strategic credibility. However, this process is private and does little to build broader brand awareness. As a DealMaker Tech analysis notes, there’s a compelling argument that for many, the benefits are limited:
The process of raising VC capital doesn’t elevate your brand, and so its benefits are confined to the capital involved.
– DealMaker Tech analysis, The Power of Community: Investor Crowdfunding vs. Venture Capital
Equity Crowdfunding, particularly for B2C companies, flips this model on its head. The fundraising campaign itself becomes a massive marketing event. By turning hundreds or thousands of small investors into shareholders, you are simultaneously creating a powerful army of brand evangelists. These are your first customers, your most vocal supporters, and your most honest feedback channel. This can lead to a « negative Cost Per Acquisition (CPA) » scenario, where the people giving you money also become your customers, a dynamic VCs simply cannot replicate.
The following table, based on an analysis by DealMaker Tech, breaks down the strategic differences in customer acquisition between the two models.
| Dimension | Venture Capital | Equity Crowdfunding |
|---|---|---|
| Primary Customer Acquisition Benefit | Strategic network introductions and B2B warm leads | Thousands of small investors converting to brand evangelists and early adopters |
| Best Suited For | B2B SaaS and enterprise solutions | B2C consumer-facing products and services |
| Acquisition Mechanism | Investors leverage portfolio network for strategic introductions, reducing sales cycles | Marketing the fundraising campaign itself generates brand awareness and community building |
| Implicit Cost Per Acquisition | Low CPA for B2B via network access (value added beyond capital) | Potentially ‘negative CPA’ where investors become customers simultaneously |
| Long-term Acquisition Support | Ongoing strategic guidance in building professional sales teams | Initial boost requires company to build sustainable acquisition channels post-campaign |
| Speed to First Customers | Faster for enterprise deals requiring credibility and warm introductions | Faster for consumer products where community and social proof drive early adoption |
The Premature Scaling Mistake That Bankrupts 70% of Seed-Funded Startups
There is no greater danger to a freshly funded startup than premature scaling. It’s the act of stepping on the accelerator before you’ve built the engine and checked the steering. You’ve secured your first significant seed round, and the pressure – from investors, the market, and your own ego – is to grow, now. You hire a big sales team, launch in multiple cities, and spend heavily on marketing. Yet, in most cases, this leads directly to ruin. The data is damning: a staggering 74% of high-growth tech startups fail not from lack of funding, but from scaling up too soon, according to extensive analysis from the Startup Genome Report.
Premature scaling is spending money to acquire customers before you have validated a profitable, repeatable model for doing so. It’s confusing cash flow with profit and growth with progress. The core mistake is shifting focus from nailing the product and achieving product-market fit (PMF) in a single, defined market to simply chasing top-line growth across multiple fronts. Your cash burn rate skyrockets, your unit economics are unsustainable, and the company collapses under its own weight when the next funding round fails to materialise.
The single burning match in a vast expanse is the perfect metaphor for a prematurely scaled startup. The initial flame of funding is bright but finite. If it’s used to chase distant horizons before securing its immediate surroundings, it will simply burn out, leaving nothing but smoke. The disciplined founder resists the temptation. They use seed funding to dominate one niche, one city, or one customer segment until the process of acquiring and serving those customers is as predictable and profitable as a factory assembly line. Only then is it time to pour fuel on the fire.
Cautionary Tale: The Housing.com Collapse
Housing.com, a real estate platform, raised huge sums of venture capital, achieving a valuation over £100 million. It aggressively scaled across multiple cities before establishing a profitable model in any single one. Founder Rahul Yadav later admitted the critical error: « We scaled up too fast. We should have cracked one market completely before venturing out into any other market. I would scale up for profitability than for burning. » The unsustainable cash burn led to massive layoffs and a strategic collapse, a stark reminder that capital cannot substitute for a validated business model.
When Exactly Should You Transition Your Profitable Side-Hustle Into a Limited Company?
For many founders, the journey begins not in a boardroom, but as a side-hustle. It’s profitable, it’s growing, but it’s still operating under your personal name as a sole trader. The question of when to make the leap to a Limited (Ltd) Company is one of the most critical early-stage decisions, and getting the timing wrong can have significant financial and legal consequences. This isn’t a matter of « if, » but « when, » and the answer is dictated by specific business triggers, not arbitrary feelings of being « ready. »
The primary benefit of a Ltd Company is the creation of a « corporate veil » – a legal distinction between your personal assets and the company’s liabilities. As a sole trader, if the business fails or is sued, your home, your car, and your savings are all at risk. As a director of a Ltd company, your liability is generally limited to the value of your shares. This protection becomes non-negotiable the moment your business starts interacting with larger entities, taking on debt, or hiring staff. Most large corporate clients, for instance, have procurement policies that forbid them from contracting with sole traders due to the perceived risk and lack of legal substance.
Beyond liability, the transition is driven by tax efficiency and investment readiness. As a sole trader, all profits are taxed as personal income, which can quickly push you into higher tax brackets (40-45%). Generally, once your annual profits start to exceed the £50,000-£60,000 threshold in the UK, it becomes more tax-efficient to operate as a Ltd Company. You pay Corporation Tax on profits and can then decide how to extract the remaining cash through a combination of a modest salary and dividends, offering far greater flexibility. Crucially, if you ever plan to seek investment, you must be a limited company. Investors buy equity (shares), which only exist in a corporate structure. Furthermore, the highly attractive UK tax relief schemes for investors, like SEIS and EIS, are only applicable to limited companies meeting strict criteria about their age and trading history. Incorporating too late can make your startup ineligible for these schemes, rendering it « uninvestable » for most UK angels.
How to Force Large Corporate Clients to Accept 15-Day Payment Terms?
Cash flow is the lifeblood of any SME, and nothing kills it faster than a large corporate client imposing 60, 90, or even 120-day payment terms. While you may feel powerless against a procurement department of a FTSE 250 company, you have more leverage than you think. The key is not to « force » them with aggression, but to strategically reframe the negotiation from a simple price discussion to a holistic value proposition where prompt payment is a non-negotiable component of the service you provide.
First, you must build the payment terms into your initial proposal and contract, not as an afterthought. Frame shorter terms as a standard component of your « premium » or « agile » service offering. Your position should be: « To deliver the level of responsiveness and dedicated service you require, we operate on a tight cash flow cycle, which is why our standard terms are 15 days. » This links prompt payment directly to the quality of service they will receive. You can also build in a « prompt payment discount » (e.g., 2% for payment within 10 days) which reframes the cost. A procurement manager who is measured on savings will find it hard to ignore a 2% discount, effectively getting them to argue *for* paying you quickly.
Second, leverage the legal and ethical frameworks available in the UK. The Prompt Payment Code (PPC) is a voluntary code of practice where signatories commit to paying 95% of their small business suppliers within 30 days. Many large corporates are signatories. While not legally binding in the same way as a contract, you can tactfully reference it during negotiations: « As a signatory of the Prompt Payment Code, I’m sure you’ll appreciate why our 15-day terms are designed to align with the spirit of the code’s commitment to SMEs. » Finally, for any new client, insist on a deposit or upfront payment for a portion of the project. If they push back, it’s a major red flag about their future payment behaviour. A client who is unwilling to share any of the initial risk is a client you should be prepared to walk away from. Sometimes the best negotiation tactic is the willingness to say no.
How to Legally Separate Your Personal Savings From Your UK Business Liabilities?
The most fundamental reason to form a limited company is to create a « corporate veil, » a legal separation between you and your business. In theory, if the business incurs debts it cannot pay, creditors can only claim the company’s assets, not your personal home or savings. However, many UK founders are shocked to discover how easily this veil can be pierced, leaving their personal wealth exposed. The most common way this happens is through the Director’s Personal Guarantee (DPG).
When an SME seeks a business loan from a high-street bank, the bank will almost universally demand a DPG. This is a contractual agreement where you, the director, personally promise to repay the loan if the business defaults. In a single signature, you effectively nullify the primary benefit of limited liability for that specific debt. Your personal assets are now on the line. While this is standard practice, it is not a non-negotiable demand. As a founder, your job is to negotiate the *terms* of the guarantee to minimise your personal exposure. For example, experienced founders will negotiate to cap the guarantee at a specific percentage of the loan (e.g., 50%) rather than an unlimited amount, or offer a charge over a specific business asset as an alternative. Another tactic is to include a « sunset clause, » where the guarantee is automatically released once the loan balance falls below a certain threshold.
It’s important to note that government-backed schemes often provide better protection. For instance, the Recovery Loan Scheme explicitly prohibits lenders from requiring personal guarantees for loans below a certain size. This sets a valuable precedent you can reference in commercial negotiations. The ultimate separation comes from funding your business with sources that don’t require personal guarantees at all, such as equity investment (where the risk is borne by the investor) or by generating enough profit to self-fund growth. The goal is to build a fortress around your personal finances, and that means treating every request for a personal guarantee not as a formality, but as a high-stakes negotiation where your personal financial security is on the table.
Key takeaways
- Sequence Your Funding: Start with non-dilutive capital like Government Start Up Loans and cash flow optimisation before ever considering selling equity.
- Dilution Is Permanent: Giving away a large chunk of equity to an early-stage angel investor is the most expensive money you will ever take, drastically reducing your final exit value.
- Liability Is Negotiable: A Limited Company is your first line of defence, but you must actively negotiate the terms of Director’s Personal Guarantees to truly protect your personal assets.
How to Leverage Your Property Equity to Fund High-Growth Business Ventures?
For many established UK founders, one of the largest and most under-utilised sources of growth capital is sitting right under their feet: the equity in their personal property. While mixing personal and business finances should always be done with extreme caution, using your home equity can be a uniquely fast and relatively cheap way to inject £50,000 – £250,000+ into your business for a pivotal moment, such as acquiring a competitor, purchasing key equipment, or funding a major marketing campaign.
This is not about taking on unnecessary risk, but about making a calculated investment in your own venture. If you have a proven business model and need capital to scale, the interest rate on a remortgage or secured loan (often 3-7%) will almost always be significantly lower than the cost of equity (where investors expect returns of 20-40% or more). You are essentially choosing to pay a bank a low-interest rate to retain 100% of the upside from your growth, rather than giving a large slice of that upside to an external investor. The decision hinges on your confidence in your ability to generate a return on the capital that is substantially higher than the cost of borrowing it.
In the UK, there are three primary routes to release this equity, each with its own trade-offs in terms of speed, cost, and flexibility. A full remortgage is often the cheapest in terms of interest rate but can be the slowest. A further advance from your current lender is faster but offers less flexibility. A secured loan (or « second charge mortgage ») is the fastest way to get funds but comes with the highest interest rates. The right choice depends entirely on the urgency of your capital need and your personal financial situation.
The following table provides a comparison of the main options for releasing property equity for business funding in the UK.
| Product Type | Speed to Funds | Flexibility | Total Cost | Impact on Main Mortgage | Best For |
|---|---|---|---|---|---|
| Remortgage (Full refinance) | 4-8 weeks | High – Can switch lender for better rate | Lowest interest rates (typically 2-4% above base rate) | Replaces existing mortgage entirely, resets term | Founders with significant equity (60%+ LTV) seeking lowest long-term cost, willing to wait |
| Further Advance (Top-up from existing lender) | 2-4 weeks | Moderate – Limited to current lender’s products | Moderate (typically 1-2% above your main mortgage rate) | Sits alongside existing mortgage, separate agreement | Founders with good relationship with current lender, needing faster access than full remortgage |
| Secured Loan (Second charge) | 1-2 weeks | High – Independent of main mortgage lender | Highest (typically 4-8% above base rate) | No impact on main mortgage terms or lender | Founders needing quick access, or with credit issues preventing remortgage, or fixed-rate mortgage with high early repayment charges |
Now that you have a comprehensive overview of the strategic funding landscape, the next logical step is to apply this framework to your own specific business situation. This means conducting a thorough audit of your current financial position, growth objectives, and personal risk tolerance to determine the optimal funding sequence for your journey.
Frequently Asked Questions on UK Company Funding and Structure
At what profit level does a UK limited company become more tax-efficient than operating as a sole trader?
Generally, when annual profits exceed approximately £50,000-£60,000, the combination of Corporation Tax (currently 19-25% depending on profit level) plus Dividend Tax on distributions becomes more efficient than paying Income Tax (20-45%) and Class 4 National Insurance (9-2%) as a sole trader. However, the exact threshold varies based on personal circumstances and current tax bands. Consult an accountant for personalized calculation.
Why must the transition to a limited company happen before seeking external investment?
UK tax relief schemes like SEIS and EIS, which offer substantial incentives to investors (up to 50% income tax relief for SEIS), have strict eligibility criteria tied to the company’s age and date of first commercial sale. A company must apply for Advanced Assurance before fundraising, and most angels and VCs will not invest in sole traders because they cannot receive equity stakes in unincorporated entities. Delaying incorporation can disqualify your business from these crucial investor incentives.
What specific business events trigger the immediate need for limited company status?
Key triggers include: (1) Signing your first large B2B corporate contract, as most procurement departments require suppliers to be limited companies for legal and insurance reasons; (2) Hiring your first employee, as employment contracts and PAYE obligations are more professionally structured under a Ltd Co; (3) Taking on a commercial property lease, where landlords typically require limited company tenants; (4) Reaching the £85,000 VAT registration threshold, where incorporation provides clearer accounting separation.