Successfully moving from residential to commercial property is not an upgrade in scale, but a fundamental shift in business strategy that requires new tools and a different mindset.
- Unlike residential Assured Shorthold Tenancies, commercial Full Repairing and Insuring (FRI) leases transfer nearly all property-related risks and costs to the tenant, providing landlords with powerful asymmetric leverage.
- Advanced financial vehicles like Self-Invested Personal Pensions (SIPPs) allow for the tax-free purchase and growth of commercial assets, a structure unavailable to residential investors.
Recommendation: Before making the transition, experienced landlords must master the legal frameworks and financial instruments unique to the commercial sector to truly unlock its potential for wealth generation and asset protection.
For many experienced residential landlords in the UK, the cycle is familiar: chasing rent, managing constant maintenance requests, and navigating the increasingly tenant-friendly legal landscape of Assured Shorthold Tenancies (ASTs). The appeal of commercial real estate—with its promise of longer leases and higher yields—seems like the next logical step up the property ladder. It represents a move towards more professional, less hands-on asset management.
The common advice often stops there, focusing on the superficial benefits. Many believe the transition is simply a matter of scale. However, this perspective overlooks the profound strategic, legal, and financial differences that define the commercial property sector. The real advantage isn’t just a longer lease; it’s the underlying power dynamic that shifts entirely in the landlord’s favour. The opportunity isn’t just a higher yield; it’s the ability to use sophisticated corporate and pension structures to build and protect wealth in ways that are simply impossible in the residential market.
But if the core of this transition is not about buying bigger properties, but about adopting a new strategic playbook, what does that mean in practice? The key is to stop thinking like a residential landlord and start operating like a commercial portfolio director. This involves mastering the legal instruments that create liability firewalls, understanding the financial vehicles that deliver unmatched tax efficiency, and making strategic choices based on risk-adjusted returns rather than gross yield alone.
This guide provides the framework for that transition. We will dissect the critical differences that separate the two asset classes and provide a strategic roadmap for navigating the commercial property landscape. By focusing on the structural advantages and potential pitfalls, you will gain the insights needed to move beyond the limitations of buy-to-let and build a truly robust commercial portfolio.
To help you navigate this strategic shift, this article breaks down the essential components for a successful transition from residential to commercial property investment. The following sections provide a clear, step-by-step examination of the legal, financial, and operational knowledge you will need to master.
Summary: A Director’s Guide to Transitioning into Commercial Real Estate
- Why Commercial Property Leases Offer Landlords Ten Times More Legal Protection?
- How to Purchase Your Own Business Premises Tax-Free Using a UK SIPP?
- Retail Shops vs Light Industrial Units: Where Should Beginner Commercial Landlords Start?
- The Empty Unit Error That Buries Commercial Landlords in Massive Business Rates
- When Must You Demand a Break Clause During a 10-Year Commercial Lease Negotiation?
- Limited Company vs Personal Name: Which Is Better for Buying Rental Properties?
- How to Legally Separate Your Personal Savings From Your UK Business Liabilities?
- How to Shield Your Accumulated Wealth From Unexpected Civil Lawsuits and Creditors?
Why Commercial Property Leases Offer Landlords Ten Times More Legal Protection?
The single most significant shift when moving from residential to commercial property is the nature of the lease agreement. While residential landlords are bound by the heavily regulated and tenant-favouring framework of Assured Shorthold Tenancies (ASTs), the commercial world operates on a different principle: asymmetric leverage in favour of the landlord. This is primarily achieved through the Full Repairing and Insuring (FRI) lease, a cornerstone of UK commercial property investment.
An FRI lease fundamentally alters the landlord’s responsibilities. Unlike an AST where the landlord is responsible for structural repairs, building insurance, and most internal maintenance, an FRI lease transfers these obligations almost entirely to the tenant. The tenant is contractually bound to repair, maintain, and insure the property, effectively making them the custodian of the asset’s physical condition. In fact, property legal experts confirm that most commercial leases are FRI leases in the UK, establishing this as the professional standard.
This transfer of responsibility culminates at the end of the lease with the ‘Schedule of Dilapidations’. This is a legally enforceable document detailing every repair, reinstatement, or decoration the tenant must complete to return the property to its original state. There is no concept of « fair wear and tear » as there is in residential lettings. If the tenant fails to perform the works, the landlord can claim a significant cash settlement. This mechanism ensures your asset is preserved or you are compensated for its degradation, a level of protection unimaginable in the buy-to-let market.
| Responsibility Category | Residential AST (Landlord Burden) | Commercial FRI Lease (Landlord Burden) |
|---|---|---|
| Structural Repairs (roof, walls, foundations) | Landlord responsible | Tenant responsible under FRI |
| Building Insurance | Landlord arranges and pays | Tenant pays premium (landlord arranges) |
| Interior Maintenance (plumbing, electrics, fixtures) | Landlord typically responsible | Tenant fully responsible |
| External Repairs and Decorations | Landlord responsible | Tenant responsible under FRI |
| End-of-Lease Property Condition | Fair wear and tear accepted | Schedule of Dilapidations enforced—tenant pays to restore or compensate |
| Security of Tenure | Strong tenant rights (hard to evict) | Can contract out of Landlord & Tenant Act 1954 for full control |
This structure provides a predictable, low-touch income stream and robust asset protection, representing the core strategic advantage of commercial property over residential. It transforms the landlord’s role from a hands-on manager to a strategic asset owner.
How to Purchase Your Own Business Premises Tax-Free Using a UK SIPP?
One of the most powerful tools for financial vehicle optimisation available to commercial property investors is the Self-Invested Personal Pension (SIPP). A SIPP allows you to hold commercial property directly within your pension wrapper, offering unparalleled tax advantages. The property purchase is made with pension funds, and any rental income generated flows directly back into the SIPP, completely free from income tax. Furthermore, any capital growth on the property is exempt from Capital Gains Tax (CGT) when it is eventually sold.
This is a particularly potent strategy for business owners looking to acquire their own premises. Instead of paying rent to an external landlord, your business can pay a market-rate rent directly to your own SIPP. This effectively transforms a business expense into a tax-free pension contribution, building your personal retirement wealth with your company’s funds. It’s a closed-loop system for wealth creation that is unique to commercial property.
However, this strategy demands meticulous adherence to HMRC rules. All transactions must be conducted at ‘arm’s length’, meaning the property price and rental value must be independently verified by a RICS-qualified surveyor. Failure to comply can be catastrophic. As recent enforcement cases show, HMRC can impose penalties up to 55% of the property’s value for non-compliant transactions. This highlights the necessity of professional advice and strict procedural discipline. Using a SIPP is not a casual decision; it is a professional financial manoeuvre.
Your Action Plan: The SIPP Commercial Property Purchase Process
- Establish & Fund: Open a SIPP with a provider permitting direct commercial property investment and ensure it is sufficiently funded through contributions or transfers.
- Valuation: Identify a suitable property and instruct a RICS surveyor to provide an independent ‘at arm’s length’ market valuation to satisfy HMRC requirements.
- Legal Ownership: Appoint a solicitor to handle the conveyancing. The legal owner will be the SIPP trustee, not you personally, creating a clear separation.
- Lease Formalisation: If leasing to your own business, establish a formal commercial lease at the market rent verified by the surveyor. This is a non-negotiable step.
- Income & Growth: All rental income flows into the SIPP tax-free and grows sheltered from capital gains tax, ready for your retirement.
Mastering the SIPP mechanism is a clear differentiator between an amateur and a strategic commercial investor, allowing you to leverage the tax system itself to accelerate portfolio growth.
Retail Shops vs Light Industrial Units: Where Should Beginner Commercial Landlords Start?
Not all commercial property is created equal. For a landlord transitioning from the residential sector, the choice of asset class is critical. The two most common entry points are high street retail and light industrial units. While retail may seem more familiar, a strategic analysis of risk-adjusted yield and management intensity strongly points towards industrial property as the superior starting point for most new commercial landlords.
High street retail is grappling with post-pandemic shifts to e-commerce, leading to higher tenant turnover and a greater risk of business failure. This requires intense monitoring of tenant financial health, known as ‘covenant strength’. Conversely, the logistics and light industrial sector is booming, driven by the very e-commerce trend that challenges retail. These tenants often have stronger covenants and sign longer, more stable leases. The performance data backs this up; while All Property returned 5.5%, a recent MSCI index shows UK industrial recorded average total returns of 8.3% in 2024, outperforming retail.
Beyond returns, the management burden differs significantly. Retail units involve high public footfall, constant aesthetic considerations, and complex planning restrictions. Industrial units, by contrast, are functional spaces with lower public scrutiny and fewer hands-on issues.
| Factor | High Street Retail (Score 1-5) | Light Industrial/Logistics (Score 1-5) |
|---|---|---|
| Tenant Turnover Frequency | 4 (High—retail vulnerable to consumer trends) | 2 (Low—longer leases, stable logistics demand) |
| Covenant Monitoring Intensity | 5 (Very High—retail failures common post-pandemic) | 2 (Low—e-commerce & supply chain tenants more stable) |
| Building Complexity (HVAC, loading bays, plant) | 3 (Moderate—customer-facing fit-out, climate control) | 4 (High—loading capacity, vehicle access, floor strength critical) |
| Hands-On Issue Likelihood | 4 (High—public footfall, aesthetic maintenance, planning restrictions) | 2 (Low—functional spaces, less public scrutiny) |
| Overall Management Burden | 16/20 (Higher Intensity) | 10/20 (Lower Intensity) |
While industrial buildings can have complex elements like loading bays and high-capacity power, these are managed by the tenant under an FRI lease. For the landlord, the lower tenant turnover and reduced monitoring intensity make industrial a far more passive and strategically sound investment for a beginner commercial investor.
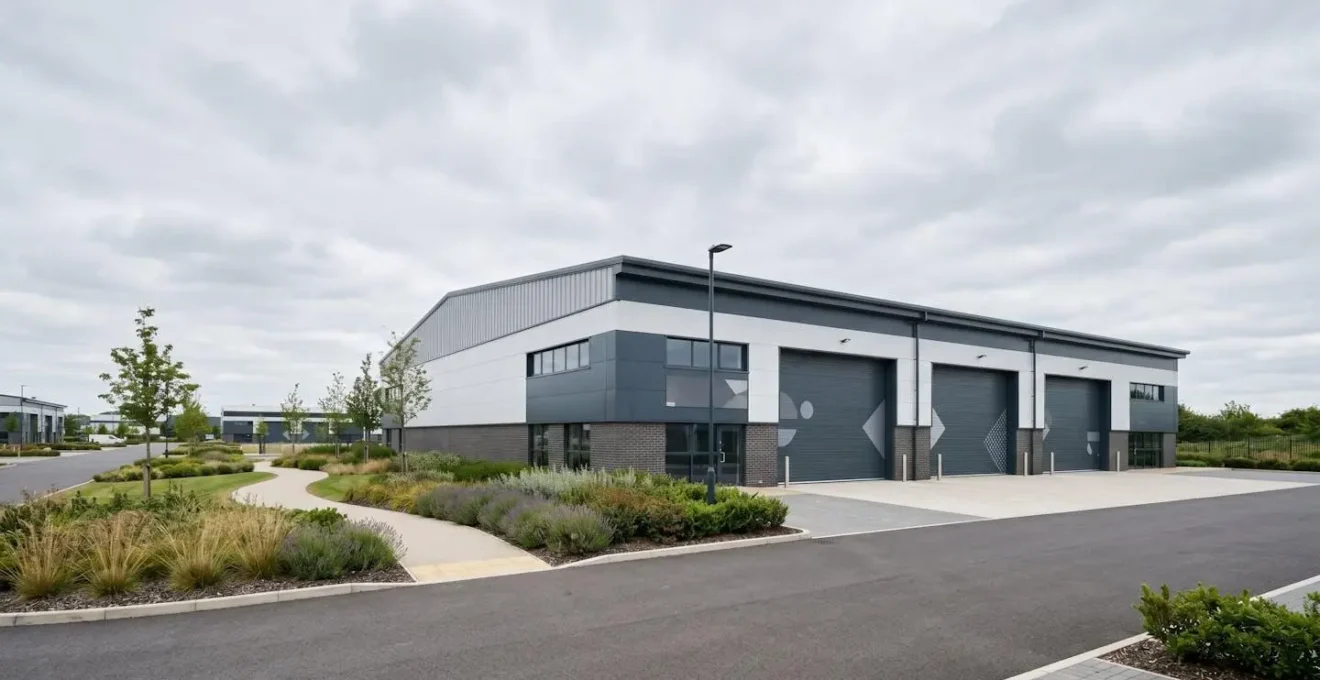
The choice is clear: while retail offers familiarity, light industrial offers superior returns, lower management intensity, and aligns with long-term economic trends, making it the smarter entry point into the commercial market.
The Empty Unit Error That Buries Commercial Landlords in Massive Business Rates
One of the harshest financial lessons for new commercial landlords is the reality of business rates on vacant properties. Unlike residential property, where council tax liability on an empty home is often reduced or delayed, the commercial sector is unforgiving. A vacant unit can quickly transform from a passive asset into an aggressive liability that erodes your returns. This is a critical risk that requires proactive vacancy management, not a passive wait-and-see approach.
Under current regulations, the grace period is alarmingly short. According to official UK government rules, empty commercial properties receive only 3 months’ exemption before full business rates become payable. This period is extended to six months for industrial premises, but thereafter, the landlord is liable for 100% of the business rates bill. With rates often equating to around 50% of the property’s annual rental value, an extended vacancy can wipe out an entire year’s profit, even from other properties in your portfolio.
This « empty unit error » has buried many unprepared landlords. Assuming that you can simply wait for the perfect long-term tenant is a residential mindset that is financially ruinous in the commercial sphere. A portfolio director, by contrast, actively deploys strategies to mitigate this liability from the moment a unit becomes vacant. This involves understanding the legal mechanisms available to reset exemption periods or qualify for reliefs, turning a potential disaster into a managed cost.
Your Checklist for Mitigating Empty Business Rates
- Points of Contact: Immediately engage with the local council’s business rates department and the Valuation Office Agency (VOA) to confirm the property’s status and Rateable Value.
- Collect Evidence: Document the property’s condition. If it is undergoing major renovations that render it unusable, gather photographic evidence and contractor reports to support a claim to have it removed from the ratings list.
- Check for Coherence with Exemptions: Does the property qualify for an exemption? Cross-reference its Rateable Value against the current threshold (below £2,900) and check if it is a listed building or prohibited from occupation by law.
- Explore Strategic Lettings: Identify potential short-term tenants. A letting of at least 13 weeks can reset the exemption clock. Also, consider letting to a registered charity, which can claim 80% mandatory relief.
- Plan for Action: Prioritise your strategy. Is an appeal to the VOA more viable, or is securing a short-term charity let the quickest way to mitigate the liability? Create a timed action plan.
Treating business rates as an active management challenge, rather than a passive bill, is a hallmark of a professional commercial property investor.
When Must You Demand a Break Clause During a 10-Year Commercial Lease Negotiation?
Long leases are a primary attraction of commercial property, offering income security far beyond what residential can provide. While typical commercial lease terms range from 3 to 25 years, a 10-year or 15-year term provides exceptional stability. However, locking yourself into a long lease without flexibility can be a strategic error, especially in a volatile market or with a tenant whose long-term viability is uncertain. This is where the break clause becomes a crucial negotiation tool.
A break clause gives either the landlord or the tenant (or both) the right to terminate the lease at a specified point before its official end date, provided certain conditions are met. As a landlord, you should demand a break clause in several key scenarios. Firstly, when leasing to a new or unproven business (a weak ‘covenant’). A break clause at year 3 of a 10-year lease allows you to regain control of the asset if the tenant’s business falters, preventing you from being locked into a failing tenancy. Secondly, if you anticipate a significant rise in market rents, a break clause allows you to terminate the current lease and re-let the property at a higher rate, optimising your yield.
The conditions attached to a break clause are paramount. They almost always require the tenant to have paid all rent, be in full compliance with their repair obligations, and to yield up ‘vacant possession’. Any failure to meet these conditions precisely can invalidate the break, making it a powerful tool of leverage for the landlord.
Case Study: The Strategic Fintech Break Clause
A fintech firm signed a 6-year lease but negotiated a 3-year break clause. This gave the landlord the confidence to let to a young company, securing a tenant in a new building. When the firm’s rapid growth required a larger space, they successfully exercised the break clause after giving six months’ notice and fulfilling all their dilapidations obligations. For the landlord, this meant a proven, well-maintained unit was returned to the market ready for a new, potentially longer-term tenant. The case shows that a well-drafted break clause provides flexibility for tenants while giving landlords control and leverage during negotiations.
A break clause is not a sign of weakness; it is a sophisticated risk management device. It allows you to offer the security of a long lease while retaining strategic options to protect your investment and maximise its future performance.
Limited Company vs Personal Name: Which Is Better for Buying Rental Properties?
For residential landlords, buying in a personal name is common. In the commercial property world, however, using a Limited Company—specifically a Special Purpose Vehicle (SPV)—is the professional standard. The reasons go far beyond simple tax rates and touch upon liability, financing, and future growth. Choosing the right structure is a foundational decision that establishes the liability firewall for your entire portfolio.
The most immediate benefit of a limited company is liability protection. If the property is held by the company, any legal claims or financial liabilities are limited to the assets within that company. Your personal assets, including your family home and savings, are shielded. While lenders will almost always require a Personal Guarantee (PG) for a mortgage, the corporate veil still protects you from other potential civil claims, such as those from a ‘slip and fall’ incident on the premises.
From a tax perspective, the benefits are compelling. Rental income is subject to Corporation Tax rather than personal Income Tax. With current Corporation Tax rates of 19-25%, this is significantly lower than the 40-45% higher-rate income tax many landlords face. This allows you to retain more profit within the company, which can then be used to reinvest and acquire more properties, accelerating portfolio growth in a way that is difficult to achieve when profits are extracted and taxed at personal rates.
Perhaps the most overlooked advantage is VAT. A VAT-registered limited company can reclaim the 20% VAT on the purchase price of a commercial property if it ‘opts to tax’ the building. This provides a massive, immediate cash-flow advantage that is simply unavailable to personal owners.
| Factor | Personal Ownership | Limited Company (SPV) |
|---|---|---|
| Commercial Property Norm | Less common; lenders less comfortable | Professional standard for commercial assets |
| Liability Protection | Unlimited personal liability | Limited liability (but Personal Guarantees still required by lenders) |
| Tax on Rental Income | Income Tax at personal rate (20-45%) | Corporation Tax (currently 19-25%) |
| Profit Retention & Reinvestment | Extract profits = higher-rate Income Tax | Retain profits in company at Corp Tax rate for faster growth |
| Capital Gains Tax on Sale | CGT at 10-28% (depending on rate) | Corporation Tax on gains (19-25%), but distributions taxed again |
| VAT Recovery on Purchase | Cannot reclaim VAT | Can reclaim 20% VAT if company opts to tax (major cash-flow advantage) |
| Administrative Burden | Lower—personal tax return | Higher—company accounts, CT600, confirmation statements |
While running a limited company involves more administration, the advantages in liability protection, tax efficiency, and financing credibility make it the undisputed choice for any serious commercial property investor.
How to Legally Separate Your Personal Savings From Your UK Business Liabilities?
Once you have established a limited company as your investment vehicle, the ‘corporate veil’ theoretically separates your business liabilities from your personal assets. However, this protection is not absolute. It can be pierced if you fail to maintain a strict legal and financial separation between yourself as a director and the company as a separate legal entity. The primary tool for managing this separation is the Director’s Loan Account (DLA).
The DLA is a record kept in the company’s accounts of all money that flows between you and your company that isn’t salary, dividends, or expense reimbursement. If you lend the company money to help with a deposit, it’s recorded as a credit on your DLA (the company owes you money). If you take money out of the company for personal use, it’s recorded as a debit (you owe the company money). Maintaining a clean and accurate DLA is the single most important element in proving to HMRC and the courts that the company is a genuine, separate entity.
The most common error is allowing the DLA to become ‘overdrawn’—meaning you have taken out more money than you have put in. If an overdrawn loan is not repaid within 9 months of the company’s year-end, HMRC will levy a punitive s455 tax charge, currently 33.75% of the outstanding loan amount. This tax is designed specifically to penalise the mingling of personal and company funds. The cardinal rule is simple: never use the company bank account as a personal piggy bank. All transactions must be meticulously documented, and separate bank accounts are non-negotiable.
For more complex portfolios, a Holding Company (‘HoldCo’) can be established to own the shares of several subsidiary property companies (‘PropCos’). This structure isolates risk, so that if one property venture fails, its liabilities are contained within its own PropCo and do not threaten the other assets in the group or the HoldCo itself. This is the ultimate expression of the liability firewall.
Managing Your Director’s Loan Account: The Core Rules
- Meticulous Record-Keeping: Every transaction between you and the company must be documented with date, amount, purpose, and agreed repayment terms.
- Separate Bank Accounts: Maintain completely separate bank accounts for personal and business finances. Never mingle funds.
- Avoid Overdrawn Balances: Monitor your DLA closely and avoid it being overdrawn at the company’s year-end to prevent the punitive s455 tax charge from HMRC.
- Charge Market-Rate Interest: If you lend money to your company, charge a formal, market-rate interest to avoid HMRC imputing a ‘benefit-in-kind’ tax charge on you.
- Annual Professional Review: Have your accountant review your DLA and inter-company transactions annually to ensure full compliance with the Companies Act and tax law.
Proper management of these structures is not just good accounting; it is the legal foundation that underpins the entire asset protection strategy of using a limited company.
Key Takeaways
- The transition to commercial property requires a strategic shift from a landlord mindset to that of a portfolio director, focusing on risk management and financial optimisation.
- Commercial FRI leases and limited company structures provide powerful legal and financial ‘liability firewalls’ that are unavailable in residential buy-to-let.
- Vehicles like SIPPs and the ability to reclaim VAT offer significant tax advantages that can accelerate wealth accumulation when managed correctly.
How to Shield Your Accumulated Wealth From Unexpected Civil Lawsuits and Creditors?
Establishing a limited company and managing your DLA correctly creates the primary liability firewall. However, this structural protection must be reinforced with a comprehensive insurance strategy. In the commercial world, where liabilities can be significant, insurance is not an administrative burden; it is an active and essential layer of your wealth-shielding mechanism. A single unforeseen event—a visitor injury, a major flood, an employee dispute—can lead to claims that could threaten a poorly insured business.
The cornerstone of this protection is Public Liability Insurance. While residential landlords may carry this, the level of cover required for a commercial property is substantially higher due to increased public access and risk. For most commercial properties, a Public Liability Insurance cover of £5m-£10m is standard practice and often a lease requirement. This protects you against potentially crippling ‘slip and fall’ claims or third-party injury lawsuits.
Beyond public liability, a suite of other policies is essential. Loss of Rent insurance is critical, as it compensates you for lost income if the property becomes uninhabitable after an insured event like a fire or flood, ensuring your cash flow remains stable during reinstatement. For properties with complex equipment like lifts or boilers, Engineering Inspection and Insurance is vital, covering both statutory inspections and costly breakdown repairs. Each policy is a tile in the mosaic of your asset protection strategy, designed to neutralise specific threats before they can impact your wealth.
A professional portfolio director does not view insurance as a cost to be minimised, but as an investment in stability and risk mitigation. It ensures that the wealth you build through strategic acquisition and management is not vulnerable to a single, unpredictable event.
Essential Insurance Policies for Commercial Asset Protection
- Public Liability Insurance: Obtain £5m-£10m of cover to protect against third-party injury claims, the most common source of large lawsuits.
- Buildings & Loss of Rent Insurance: Secure comprehensive buildings cover for perils like fire and flood, and ensure it includes a Loss of Rent clause to protect your income during downtime.
- Legal Expenses Insurance: This covers the high costs of legal defence in property disputes, lease enforcement actions, or tenant evictions.
- Employers’ Liability Insurance: If you employ anyone (even a part-time maintenance person), this is a legal requirement with a minimum cover of £5m.
- Specialist Cover (as needed): Assess the need for Engineering Inspection cover for plant/lifts or Environmental Liability for risks like asbestos, ensuring all specific asset risks are covered.
By layering these protections, you create a robust shield that allows your portfolio to grow securely, insulated from the operational and legal risks inherent in property ownership.
To put these strategies into practice, the next logical step is to conduct a thorough review of your current residential portfolio and financial position to identify the optimal path into your first commercial acquisition. Assess your risk tolerance, capital availability, and long-term goals to build a transition plan that aligns with the professional standards outlined here.