Scaling your UK property portfolio isn’t about buying more houses; it’s about building a robust, scalable business engine.
- Mastering capital velocity through methods like BRRRR is non-negotiable for rapid, sustainable growth.
- Treating leverage as a strategic tool, governed by strict risk metrics, separates professional investors from bankrupt hobbyists.
Recommendation: Shift your mindset from a passive landlord to an active ‘Portfolio CEO’ to build true, lasting real estate equity.
For many ambitious investors in the UK, the first buy-to-let property is just the beginning. The real goal is to build a portfolio that generates significant, sustainable wealth. Yet, the path from one property to three, and then beyond, is littered with challenges. Many aspiring portfolio landlords get stuck after their first or second purchase, trapped by depleted capital, rising administrative burdens, and a lack of clear strategy. The common advice—find a good location, get a good mortgage—is true, but it’s table stakes. It doesn’t explain how to create a repeatable, scalable system.
The fundamental mistake most investors make is continuing to think like a homeowner or a small-time landlord. They focus on the individual asset, not the machine that acquires and manages those assets. Scaling isn’t just doing the same thing three times; it’s about fundamentally changing your approach. It requires a shift in mindset from being a passive « landlord » to becoming an active « Portfolio CEO ». This means focusing on capital velocity, operational efficiency, and systematic de-risking.
But what if the key to scaling wasn’t just saving up for another 25% deposit over five years? What if you could build a system that recycles your initial capital in months, not years, and uses sophisticated financial structures to accelerate growth safely? This guide is built on that premise. We will move beyond the basics and break down the core business strategies you need to build a true property empire, starting with the very engine of portfolio growth: the BRRRR method.
This article provides a comprehensive roadmap for a business-first approach to property investment. Below is a summary of the core strategies we will explore to help you transition from a single-property owner to a professional portfolio manager.
Summary: A CEO’s Guide to Scaling Your UK Property Portfolio
- How to Use the BRRRR Method to Fund Your Next UK Property Acquisition?
- Limited Company vs Personal Name: Which Is Better for Buying Rental Properties?
- The Over-Leveraging Mistake That Causes Multi-Property Landlords to Go Bankrupt
- Why True Asset Accumulation in Real Estate Requires Active Daily Management?
- Boosting Rental Yields: The Renovation Strategy That Adds £200 Monthly
- Why Pushing Your Deposit From 5% to 10% Slashes Your Monthly Repayments Drastically?
- How to Use Your Stock Portfolio as Collateral for a Buy-to-Let Property Deposit?
- How to Transition Smoothly From Residential Buy-to-Lets to Commercial Real Estate?
How to Use the BRRRR Method to Fund Your Next UK Property Acquisition?
The single biggest barrier to scaling a property portfolio is capital. Waiting years to save another deposit grinds momentum to a halt. The BRRRR (Buy, Refurbish, Rent, Refinance, Repeat) method is not just a strategy; it’s the engine of capital velocity. It’s the system professional investors use to recycle their initial investment pot, allowing them to acquire new properties without having to save a full deposit from scratch each time. The goal is to force appreciation through smart refurbishment, creating new equity that can be extracted at refinancing.
The process starts with the ‘Buy’ phase. Success here is not about finding a pretty house; it’s about finding a deal. Your profit is made on the purchase. You must target properties that are 20-30% below market value, often due to being dated or in need of work. As one successful deal analysis highlights, the key is to secure a property « significantly below comparable sales because of its dated state and limited buyer competition. That discount created the margin from day one. » This margin is what makes the rest of the process possible.
Once refurbished to a high standard and rented out to a quality tenant, you approach a lender for a refinance based on the *new*, higher valuation. The aim is to refinance at 75% LTV of this uplifted value, allowing you to pull out most, if not all, of your initial capital. This recycled capital then becomes the deposit for your next project. While UK rental yields are a crucial part of the equation, with market data showing average yields between 5.4% and 7.4%, the true power of BRRRR is in manufacturing equity and maintaining momentum.
Limited Company vs Personal Name: Which Is Better for Buying Rental Properties?
As you scale, the question of ownership structure becomes critical. Holding property in your personal name is straightforward for the first purchase, but it comes with significant limitations, particularly regarding tax efficiency. Section 24 of the Finance Act 2015, often called the « tenant tax, » phased out the ability for individual landlords to deduct mortgage interest from their rental income. Instead, they now receive a tax credit based on 20% of their interest payments, a major blow for higher-rate taxpayers.
This is where operating through a Limited Company, typically a Special Purpose Vehicle (SPV), becomes a strategic imperative for the serious investor. An SPV is a company set up solely for buying and managing property. The primary advantage is that the company can still deduct 100% of the mortgage interest as a business expense before calculating its profit. This profit is then subject to Corporation Tax, not Income Tax.
The financial implications are significant. For the 2024/25 tax year, the main rate of Corporation Tax is 25%. However, as confirmed by HMRC, a lower rate of 19% applies for profits under £50,000. For a higher-rate taxpayer paying 40% income tax, the savings are immediately obvious. Setting up a company is more than a tax decision; it’s the first step in professionalising your operations. It separates your personal and business finances, provides a clear framework for accounting, and signals to lenders and partners that you are operating a genuine business—the mindset of a Portfolio CEO.
The Over-Leveraging Mistake That Causes Multi-Property Landlords to Go Bankrupt
Leverage, or using borrowed money to acquire assets, is the rocket fuel of property investment. It magnifies returns and enables rapid portfolio growth. However, it’s a double-edged sword. Mismanaged, it’s the single biggest cause of bankruptcy for multi-property landlords. The common mistake isn’t using debt; it’s using it without a robust, systematic framework for managing risk. The platitude « don’t be over-leveraged » is useless without defining what that means.
A professional investor treats leverage like a scientist, not a gambler. They operate with strict, non-negotiable metrics. This is systematic de-risking. The most critical metric is the Interest Coverage Ratio (ICR), which measures your rental income’s ability to cover your mortgage payments. Lenders typically require a minimum ICR of 125-145%, but a prudent Portfolio CEO stress-tests their entire portfolio against much harsher scenarios: what happens if interest rates rise by 3%? What if 20% of my properties are void simultaneously? If the portfolio can’t withstand that pressure on paper, it’s over-leveraged.
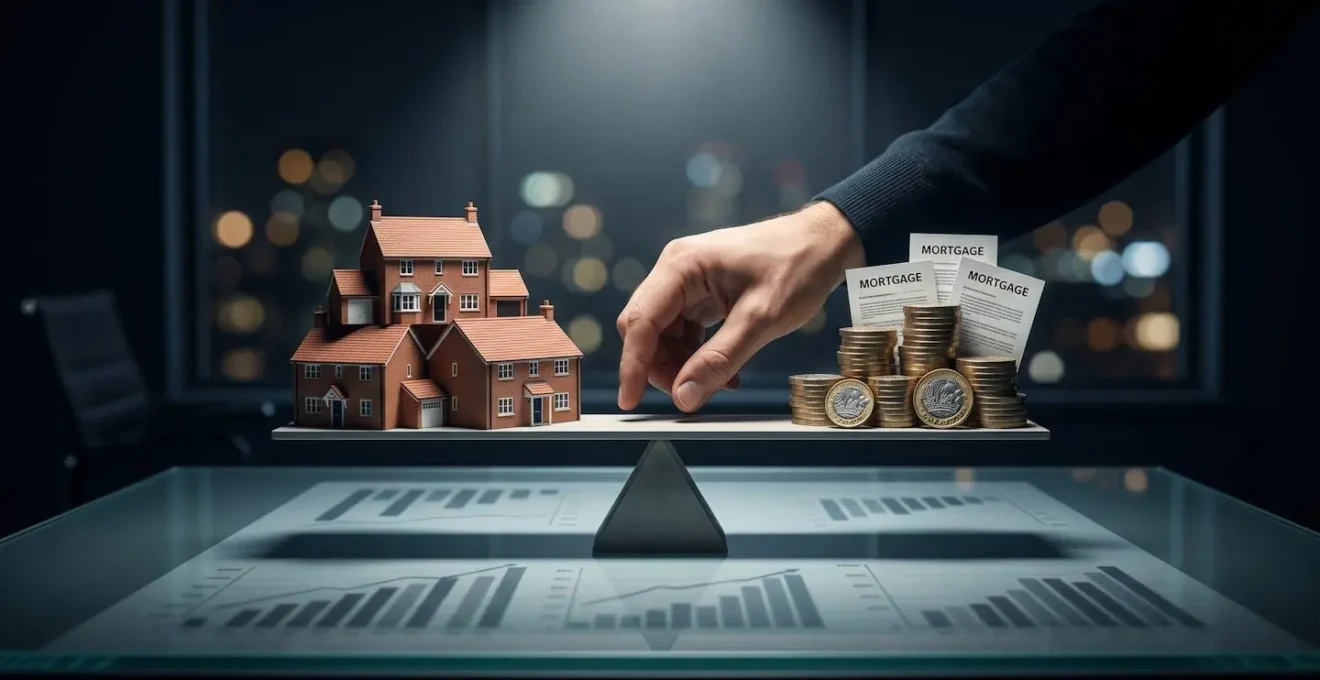
This image perfectly illustrates the delicate equilibrium a portfolio manager must maintain. It’s a constant act of balancing the drive for growth with the imperative of stability. Relying on continuous, rapid house price growth to cover high leverage is a recipe for disaster. The goal is to build a portfolio that is profitable and stable based on its rental income alone; capital appreciation is the bonus, not the foundation. Implementing a rigorous risk management system is the firewall that protects your entire asset base from a single point of failure.
Your Portfolio Risk Management Checklist
- Calculate your portfolio-wide Interest Coverage Ratio (ICR) monthly.
- Ensure rental income provides a minimum of 125-145% coverage over all mortgage payments.
- Diversify your lender exposure across multiple financial institutions to avoid concentration risk.
- Stress-test your entire portfolio against a hypothetical 3% interest rate rise and a 20% rental void period.
- Maintain a cash reserve equivalent to 6 months of expenses (mortgage, insurance, bills) for each property.
Why True Asset Accumulation in Real Estate Requires Active Daily Management?
The dream of « passive income » from property is a powerful marketing tool, but for anyone serious about building a multi-property portfolio, it’s a dangerous myth. True asset accumulation and wealth generation in real estate are the result of active, strategic management. As you scale, your role evolves from landlord to Portfolio CEO, and the complexity of the business increases exponentially. As experts from Clifton Private Finance state, « Scaling successfully requires careful planning, strategic financing, in-depth market knowledge, and effective management. » This is not a passive activity.
The shift from a casual investor to a professional one is formally recognised by lenders. Once you cross a certain threshold, the entire dynamic of securing finance changes, demanding a higher level of professionalism. This transition is not arbitrary; it’s based on the increased risk and complexity associated with larger portfolios.
Case Study: The PRA’s « Portfolio Landlord » Threshold
In the eyes of mortgage lenders, guided by Prudential Regulation Authority (PRA) rules, you typically become a portfolio landlord when you own four or more distinct mortgaged buy-to-let properties. According to analysis from Clifton Private Finance, this increased scrutiny reflects the perceived complexity of managing multiple properties. When you hit this number, lenders will no longer assess a new mortgage application in isolation. They will demand a comprehensive view of your entire portfolio’s performance, including a detailed schedule of all properties, income, costs, and existing debt. They will also scrutinise your experience, your overall financial standing, and, crucially, your business plan. You are no longer just buying a house; you are proving the viability of your entire property business.
Active management doesn’t mean you have to fix every leaking tap yourself. It means you are the active director of the business. You are managing the finances, optimising the portfolio’s performance, reviewing legals, monitoring market trends, and making strategic decisions about acquisitions and disposals. It’s a full-time mindset, even if it’s not a 9-to-5 job. Delegating tasks to letting agents or accountants is part of this, but the ultimate responsibility for the portfolio’s strategy and health remains with you, the CEO.
Boosting Rental Yields: The Renovation Strategy That Adds £200 Monthly
In a high-interest-rate environment, cash flow is king. Simply buying a property and hoping the rent covers the mortgage is a passive approach that leaves you vulnerable. A Portfolio CEO actively seeks to maximise the rental yield of every asset through strategic, value-adding renovations. The goal isn’t just to make a property « nice »; it’s to create what I call « Engineered Value »—targeting specific upgrades that directly translate into higher rental income and attract a better calibre of tenant.
The first step is forensic market analysis. Before spending a penny, you must analyse local rental comparables to understand the absolute ceiling for rent in that area for a specific type of property. What does the best two-bedroom flat in this post code rent for? What features does it have that yours doesn’t? This data-driven approach prevents over-investment in features that tenants won’t pay a premium for.
With this ceiling in mind, you can implement high-impact strategies that meet modern tenant demands. In today’s market, this often means:
- Creating dedicated work-from-home spaces: Even a small, well-lit nook with extra power sockets can be a major draw for young professionals.
- Installing smart home technology: Smart thermostats, USB-C sockets, and keyless entry systems signal a modern, well-maintained property.
- Offering all-inclusive bills packages: For HMOs or young professional lets, this can justify a significant rental premium and reduce tenant turnover by offering ultimate convenience.
- Focusing on durability: Choose durable, low-maintenance finishes over fragile luxury materials. Commercial-grade laminate flooring and hard-wearing paint save money in the long run.
A well-executed cosmetic refurbishment focused on kitchens, bathrooms, and decor can easily add £150-£200 to the monthly rent, dramatically improving your rental yield and ICR, making the entire portfolio more resilient.
Why Pushing Your Deposit From 5% to 10% Slashes Your Monthly Repayments Drastically?
The headline of this section addresses a common question from first-time homebuyers, but for a buy-to-let investor, the numbers are different—and the principle is even more critical. While residential schemes might allow for 5% or 10% deposits, the world of BTL finance operates on stricter terms. As a standard, most mortgage lenders will require an investor to put down a deposit of at least 25% of the property’s purchase price. Some lenders, particularly for higher-risk properties or investors, require as much as 40%.
So, why is this principle of a larger deposit so important? Because your Loan-to-Value (LTV) ratio is one of the most significant factors determining your mortgage interest rate. A lower LTV (achieved with a larger deposit) represents lower risk for the lender. In return for you taking on more of the risk, they reward you with a more favourable interest rate. The difference between the rate offered at 80% LTV versus 60% LTV can be substantial, directly impacting your monthly mortgage payment and, therefore, your cash flow and ICR.
Every pound you can put towards a larger deposit has a triple benefit. Firstly, it slashes your monthly repayments, freeing up cash flow that can be saved for the next deposit or used as a buffer against voids. Secondly, it improves your ICR, making you a more attractive borrower and increasing your chances of mortgage approval. Thirdly, and most importantly, it builds a crucial safety buffer. A portfolio with a lower average LTV is far more resilient to house price corrections. As a Portfolio CEO, your goal isn’t to get the biggest mortgage possible; it’s to secure the most advantageous and sustainable finance for the long-term health of your business.
How to Use Your Stock Portfolio as Collateral for a Buy-to-Let Property Deposit?
As your wealth grows, your capital may be tied up in various asset classes, such as a healthy stock and shares portfolio. The conventional route to using this wealth for a property deposit would be to sell the shares, triggering a potential Capital Gains Tax (CGT) liability and losing future growth from those investments. For a sophisticated investor, this is inefficient. An advanced strategy, typically offered by private banks, is to use your investment portfolio as collateral for a loan—a practice known as Lombard lending.
This allows you to unlock the value of your shares without selling them. You can borrow a percentage of your portfolio’s value (typically 50-70%, depending on the assets) and use that cash as a deposit for a BTL property. You continue to own the shares, benefit from any dividends and capital appreciation, and simultaneously acquire a new income-producing property. This is a powerful tool for a Portfolio CEO looking to optimise their entire balance sheet.
The attractiveness of this strategy has increased as the government has squeezed tax allowances. The annual CGT allowance, the amount of profit you can make from selling assets before tax is due, has been drastically cut. For 2024/25, the capital gains tax buffer is just £3,000. By using Lombard lending, you sidestep this tax event entirely. However, it’s not without risk. The primary danger is a « margin call » during a stock market downturn. If the value of your collateral (your shares) falls significantly, the bank can demand you either top up the loan with cash or sell shares at the worst possible time to cover the shortfall. This is a strategy for experienced investors with substantial, well-diversified portfolios and a clear understanding of the risks involved.
Key Takeaways
- Adopt a CEO mindset: Shift from being a passive landlord to an active, strategic business owner.
- Master capital velocity: Use systems like BRRRR to recycle your investment capital and accelerate growth.
- Systematically de-risk leverage: Implement strict financial metrics (like ICR and stress tests) to manage debt safely.
How to Transition Smoothly From Residential Buy-to-Lets to Commercial Real Estate?
Once you have successfully built and stabilised a residential BTL portfolio of three, four, or more properties, the natural question for a growth-oriented Portfolio CEO is: « What’s next? » For many, the answer lies in transitioning into commercial real estate. While it may seem daunting, it’s a logical progression that offers new opportunities, including longer lease terms, stronger covenants (tenants), and often higher yields. The good news is that the drive to scale remains strong among professional investors. As a recent analysis based on the English Private Landlord Survey found, « 11% of landlords, representing 15% of tenancies, were planning to expand their portfolio, » suggesting that experienced landlords continue to see financial benefits and market opportunities.
The transition should be a deliberate, educated process, not a leap of faith. The skills you’ve developed managing a residential portfolio—due diligence, financial analysis, risk management—are all transferable. However, commercial property has its own language and rules. The key to a smooth transition is to build on your existing base and learn the new game systematically.
- Start with semi-commercial properties: A shop with a flat above is an excellent stepping stone. You can use your residential expertise on the flat while learning the basics of a commercial lease on the shop.
- Learn commercial lease structures: Understand concepts like FRI (Full Repairing and Insuring) leases, where the tenant is responsible for all costs, including structural repairs.
- Build a new specialist team: Your residential mortgage broker and solicitor may not have the expertise required. You need to build relationships with commercial brokers, surveyors, and lawyers.
- Understand commercial valuations: Valuations are typically based on the rental yield and the strength of the tenant, not just comparable sales, which is a very different methodology.
By methodically building your knowledge and network, you can leverage the equity and cash flow from your residential portfolio to make a confident and successful move into the commercial sector, marking the next major phase of your journey as a property entrepreneur.
Your journey from one property to a thriving portfolio begins with the decision to operate as a business. By implementing these strategies for capital velocity, risk management, and value creation, you are building the foundations of a scalable, resilient, and highly profitable property enterprise. The next logical step is to formalise this approach by creating a comprehensive business plan for your portfolio.
Frequently Asked Questions on Advanced Property Financing
What is Lombard lending and how does it work for property?
Lombard lending allows you to borrow against your investment portfolio without selling shares, using them as collateral for property deposits while avoiding capital gains tax.
What are the risks of using stocks as collateral?
The main risk is margin calls during market downturns, which could force you to sell shares or add cash at the worst possible time, unlike traditional deposits which remain static.
Which UK institutions offer Lombard lending?
Private banks and wealth managers in the UK offer these specialized products, typically requiring substantial portfolios and meeting specific lending criteria.