Maximising high-dividend income without excessive UK tax is less about chasing the highest yields and more about executing a disciplined asset location strategy.
- Your Stocks and Shares ISA is the most powerful shield against dividend tax; its value is maximised by prioritising assets that attract the highest tax rates, such as UK REITs and high-yield corporate bonds.
- Formally splitting dividend-producing assets with a spouse via a Declaration of Trust and HMRC’s Form 17 is a critical structural tactic to double your tax-free allowance.
- Annual ‘Bed-and-ISA’ manoeuvres are an essential maintenance tool for progressively moving unsheltered assets into a tax-free environment, permanently erasing future tax liabilities.
Recommendation: Your first step should be to audit your portfolio to identify which high-tax assets are currently held outside a tax wrapper. Prioritising the migration of these specific holdings should be your immediate goal.
For UK income investors, the landscape is becoming increasingly challenging. The government’s steady reduction of the tax-free Dividend Allowance has turned what was once a minor consideration into a major strategic hurdle. Many investors are drawn to high-yield stocks, hoping to offset the rising cost of living, only to find a significant portion of their returns consumed by HMRC. The standard advice often revolves around a simple checklist: use your ISA, use your dividend allowance, and perhaps consider a pension. While correct, this approach misses the most critical element: the strategic sequencing and prioritisation of these actions.
The common perception is that all tax wrappers are equal and any high-yield stock is a good candidate for passive income. This is a costly oversimplification. The true key to tax efficiency lies not just in *what* tools you use, but *how* and in *what order*. It requires a shift in thinking from simply collecting allowances to building a robust, multi-layered tax shield around your income-producing assets. This involves understanding the nuanced differences between dividend growth and high immediate yield from a tax perspective, and recognising which assets inflict the most tax damage when left unsheltered.
But what if the secret wasn’t just about allowances, but about a defined asset location hierarchy? This guide moves beyond the basics to provide a strategic framework for UK investors. We will explore the legal mechanisms for income splitting, the critical mistake of holding certain assets outside an ISA, and the annual disciplines that can systematically eliminate your tax burden. We will deconstruct why a headline-grabbing 10% yield can be a dangerous trap and how to build a sustainable, tax-efficient income stream for the long term, including for retirement funding. This is not just a list of tips; it is a blueprint for structuring your investments to legally minimise tax and maximise your net returns.
This article provides a comprehensive roadmap for navigating the complexities of UK dividend and capital gains tax. The following sections break down the essential strategies, from foundational tactics to advanced manoeuvres, ensuring you have a complete toolkit at your disposal.
Contents: A Strategic Guide to High-Yields and Low Taxes
- How to Split High-Dividend Assets With Your Spouse to Double Your Tax Allowance?
- High Immediate Yield vs Dividend Growth: Which Strategy Minimises Tax Long-Term?
- Why a 10% Dividend Yield Is Usually a Warning Sign of Corporate Collapse?
- The Tax Penalty Mistake of Holding High-Yield Shares Outside Your ISA Wrapper
- When Exactly Must You Declare Dividend Income on Your UK Self-Assessment Form?
- How to Execute a Bed-and-ISA Strategy to Erase Future Capital Gains Tax Entirely?
- Funding Retirement Basics: The Tactic Using Top UK Dividend Aristocrat Stocks
- How to Legally Shield Your Investments From the 24% UK Capital Gains Tax?
How to Split High-Dividend Assets With Your Spouse to Double Your Tax Allowance?
One of the most direct and effective strategies for reducing your dividend tax liability is to utilise your spouse’s or civil partner’s allowances. By default, HMRC assumes that any income from jointly held assets is split 50/50. However, for married couples and civil partners, it is possible to formally declare an unequal split of beneficial interest, allowing the partner with lower income (or unused allowances) to receive a larger share of the dividends, thereby minimising the overall tax paid by the household.
This is not an informal arrangement; it requires a specific legal process. The key is to create a Declaration of Trust, a legal document that specifies the true ownership proportions of an asset, which may differ from the legal title. For example, you might own 99% of a share portfolio while your spouse owns 1%. You can then submit HMRC Form 17 (‘Declaration of beneficial interests in joint property and income’) to inform the tax authorities of this unequal split. From that point on, the dividend income will be taxed according to this 99/1 split, potentially moving significant income from a higher-rate taxpayer to a basic or non-taxpayer.
This effectively allows a couple to combine their allowances. With the current Dividend Allowance at £500 per person, a formal declaration can create a combined £1,000 tax-free dividend threshold for the household before any tax is due. This is a foundational step that should be considered before any other complex strategies, as it structurally reduces the taxable income at its source.
Action Plan: Implementing a Declaration of Trust for Income Splitting
- Determine Beneficial Interests: Agree on the actual ownership split of the shares (e.g., 99/1). This must reflect the reality of who owns the capital, not just be for tax convenience.
- Complete HMRC Form 17: You and your spouse must complete and sign the form jointly to declare the unequal beneficial interests to HMRC.
- Submit Form 17 Promptly: The form must be submitted to HMRC within 60 days of the date it was signed to be valid for the corresponding tax year.
- Ensure Consistency: To comply with tax law (ITA/S837), the share of income must exactly match the share of capital. You cannot declare a 99/1 income split on a 50/50 capital ownership.
- Maintain Evidence: Keep copies of the signed Form 17 and the Declaration of Trust as evidence of the arrangement for your tax records.
Executing this strategy correctly establishes a more tax-efficient foundation for all your unsheltered investments, making it a powerful first move in managing your overall dividend tax bill.
High Immediate Yield vs Dividend Growth: Which Strategy Minimises Tax Long-Term?
Investors often face a crucial decision: prioritise stocks with a high immediate dividend yield for instant cash flow, or opt for stocks with a lower initial yield but a strong track record of dividend growth. From a purely tax-focused perspective, the dividend growth strategy often proves superior over the long term. A high-yield stock may provide more cash today, but it also generates a larger immediate tax liability, especially for assets held outside a tax wrapper.
A dividend growth stock, conversely, starts with a smaller, more manageable dividend that may fall within your annual allowance. As the dividend grows over time, so does the share price, converting a portion of your total return into unrealised capital gains. These gains are only taxed upon sale and can be managed with the annual Capital Gains Tax (CGT) exemption. This defers and potentially reduces the overall tax burden compared to receiving high, fully taxable dividends year after year. The power of compounding works on both the dividend and the capital, all while keeping the annual tax bill lower in the initial years.
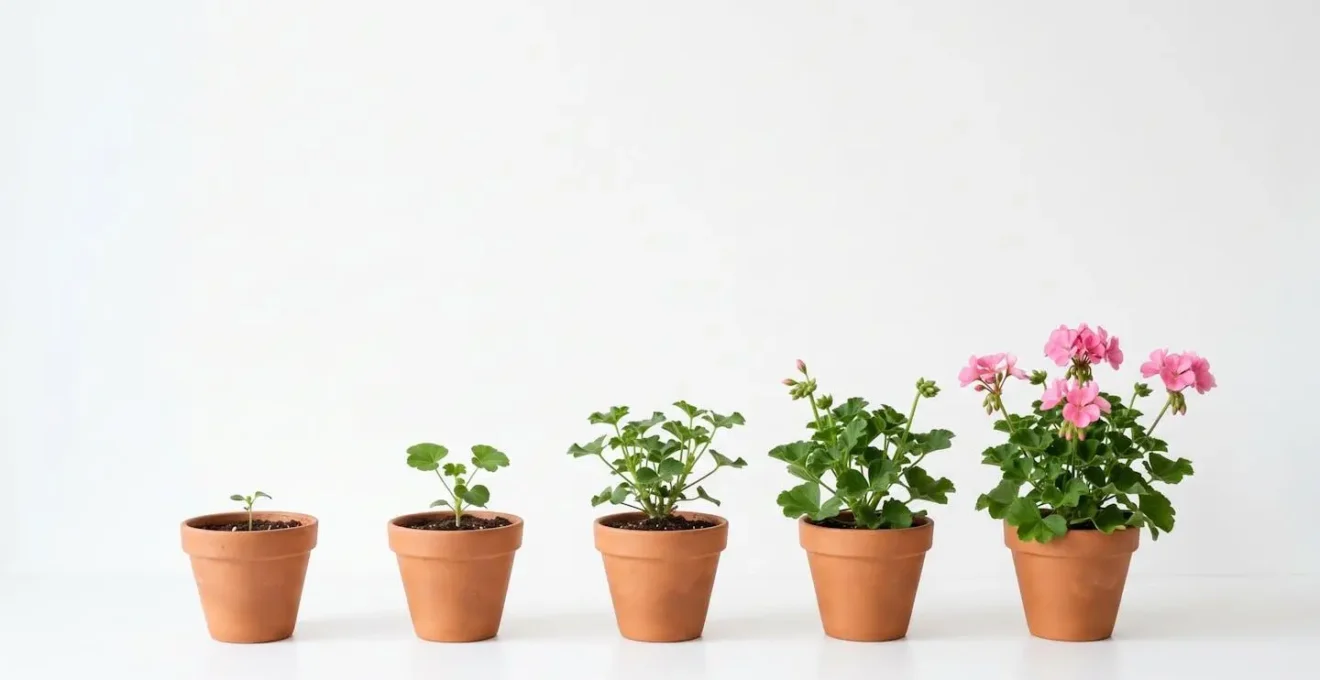
The visual progression from a seedling to a fully grown plant is a perfect metaphor for a dividend growth strategy. The initial return is small, but with time and consistent reinvestment, it blossoms into a substantial source of both income and capital appreciation. This approach aligns perfectly with a long-term, tax-minimisation mindset.
A comparative analysis over a long horizon highlights the significant difference in tax impact. While a high-yield portfolio generates more income upfront, the cumulative tax paid can erode a substantial part of the total return. The table below, based on a hypothetical £100,000 investment, illustrates how a dividend growth strategy can lead to a higher net after-tax return over 20 years, even with a lower starting yield. Of course, as a tax adviser, I must point out that holding either portfolio inside an ISA negates this issue entirely, rendering all returns tax-free.
| Strategy | Initial Yield | Growth Rate | Total Tax Paid (20 years) | Net After-Tax Return |
|---|---|---|---|---|
| High Yield Portfolio | 7% | 1% | £28,500 | £112,000 |
| Dividend Growth Portfolio | 3% | 7% | £19,200 | £134,000 |
| ISA Wrapped (Either) | N/A | N/A | £0 | Full Returns |
Ultimately, the choice depends on your financial goals, but for investors looking to build wealth efficiently over decades, a focus on quality companies with a progressive dividend policy often provides the most tax-advantageous route.
Why a 10% Dividend Yield Is Usually a Warning Sign of Corporate Collapse?
In the world of investing, a dividend yield that seems too good to be true often is. While yields in the 4-6% range can signal a healthy, mature company, a yield entering double digits (10%+) should be treated not as an opportunity, but as a significant red flag. A sky-high yield is frequently a mathematical symptom of a collapsing share price, indicating that the market has lost confidence in the company’s future prospects and its ability to sustain that dividend payment.
This is known as a ‘yield trap.’ The company may not have announced a dividend cut yet, but the plummeting stock price reflects investors’ collective expectation that one is imminent. The business may be facing severe operational challenges, overwhelming debt, or declining earnings. Paying a large dividend in such a scenario becomes unsustainable, as the company is essentially returning cash to shareholders that it desperately needs for survival or reinvestment. The inevitable dividend cut, when it comes, almost always leads to a further, often dramatic, fall in the share price, inflicting a double loss on the unsuspecting income investor: lost income and a significant capital loss.
There are exceptions, particularly in sectors like UK Real Estate Investment Trusts (REITs), where the business model is structured to pay out most of its rental income as dividends. However, even for these, a yield significantly above the sector average signals distress. Therefore, conducting thorough due diligence is not just advisable; it is essential to distinguish a sustainable high yield from a trap.
Your Checklist: High-Yield Due Diligence for UK Investors
- Check Dividend Cover Ratio: A ratio below 1.5x (meaning earnings are less than 1.5 times the dividend paid) is a major red flag, indicating the dividend is not well supported by profits.
- Analyse Free Cash Flow Payout: Scrutinise whether the dividend is paid from actual cash generated. A payout ratio above 80-100% of free cash flow is a warning sign of unsustainability.
- Review Debt-to-Equity Ratio: For non-financial firms, a ratio rising above 2.0 indicates high leverage, which can put dividend payments at risk during economic downturns.
- Monitor Director Dealings: Check for patterns of insider selling through regulatory announcements (RNS). If senior management is selling their own shares, it’s a powerful negative signal.
- Assess Historical Dividend Stability: Look for a history of consistent payments. A company with an erratic payment history or recent cuts is more likely to cut again under pressure.
Rather than being seduced by a high headline number, a prudent investor focuses on dividend quality and sustainability. A reliable 5% yield from a financially sound company is infinitely more valuable than a precarious 10% yield on the verge of collapse.
The Tax Penalty Mistake of Holding High-Yield Shares Outside Your ISA Wrapper
From a tax advisor’s perspective, the single most impactful strategy for any UK investor is the full and correct utilisation of tax wrappers, primarily the Stocks and Shares ISA. The mistake is not simply failing to use an ISA, but failing to understand the hierarchy of what should be placed inside it first. Not all investments are taxed equally, and holding your most tax-inefficient assets outside an ISA is a costly, unforced error.
The core principle is simple: your £20,000 annual ISA allowance is a shield. To maximise its effectiveness, you must use it to protect the assets that would otherwise cause the most tax damage. Certain investments are particularly punitive when held in a general investment account. For instance, UK REITs are required to deduct a 20% withholding tax on all REIT Property Income Distributions (PIDs) before you even receive them. This income is then subject to further income tax. High-yield corporate bonds are another example, with interest taxed as income at rates up to 45%.
These assets should be at the top of your list to move into an ISA. By placing them within the wrapper, both the 20% withholding tax on REIT PIDs and any further income tax on bond interest are completely eliminated. In contrast, growth stocks, which primarily generate returns via capital gains, are less urgent candidates for an ISA, as their gains are only taxed on disposal and can be managed with the annual CGT exemption.
This concept of an asset location hierarchy is fundamental to efficient tax planning. The following table, based on a priority system outlined by platforms like Interactive Investor, provides a clear framework for deciding which assets to shelter first.
| Priority | Asset Type | Tax Treatment Outside ISA | ISA Priority Score |
|---|---|---|---|
| 1 | UK REITs (PIDs) | 20% withholding + income tax | Critical |
| 2 | High-Yield Bonds | Up to 45% income tax | Very High |
| 3 | High-Dividend Stocks | 8.75%-39.35% on dividends | High |
| 4 | Growth Stocks | CGT only on disposal | Medium |
Ignoring this hierarchy is like using an umbrella to shield yourself from a light drizzle while standing unprotected in a hailstorm. By auditing your portfolio and prioritising the migration of your most heavily taxed assets into your ISA, you can dramatically and permanently reduce your investment tax bill.
When Exactly Must You Declare Dividend Income on Your UK Self-Assessment Form?
Understanding your reporting obligations to HMRC is just as important as implementing tax-reduction strategies. The rules for declaring dividend income depend on the total amount you receive in a tax year and whether you already file a Self-Assessment tax return for other reasons. A common misconception is that if no tax is due, no action is needed, but this is not always the case.
Firstly, it is crucial to remember that dividends received from assets held within an ISA or a SIPP are completely tax-free and do not need to be reported to HMRC, regardless of the amount. The following rules apply only to dividends received from investments held in a general investment account (unsheltered).
The reporting thresholds are designed to keep those with small amounts of dividend income out of the Self-Assessment system. However, as the Dividend Allowance has shrunk, more people are being brought into the reporting net. For UK tax purposes, the key date that determines which tax year a dividend falls into is the payment date, not the ex-dividend date. This is a critical detail when calculating your total dividend income for the year, which runs from 6th April to 5th April.
If your dividend income exceeds the thresholds, you must take action. Ignoring this can lead to penalties and interest charges from HMRC. The system allows for different reporting methods depending on your circumstances, from a simple phone call to full Self-Assessment registration.
Action Plan: Self-Assessment Dividend Reporting Thresholds
- Dividends under £500: If your total dividends are below the £500 allowance and you have no other reason to file a tax return, no action is generally needed.
- Dividends £500-£10,000: If you don’t already file a return, you must inform HMRC. You can do this by phone or online. For PAYE taxpayers, HMRC can often adjust your tax code to collect the tax owed.
- Dividends over £10,000: You must register for Self-Assessment. The deadline to register is the 5th of October following the end of the tax year in which you received the income.
- Already Filing Returns: If you already complete a Self-Assessment tax return (e.g., you’re self-employed), you must include all your dividend income on the return, regardless of the amount.
By accurately tracking your dividend income and adhering to these reporting rules, you can ensure you meet your legal obligations and avoid any unwelcome correspondence from HMRC.
How to Execute a Bed-and-ISA Strategy to Erase Future Capital Gains Tax Entirely?
For investors with significant holdings outside of a tax wrapper, the ‘Bed-and-ISA’ strategy is a powerful and perfectly legal manoeuvre to progressively shield assets from future dividend and capital gains tax. The process involves selling shares held in a general investment account and immediately repurchasing the same shares inside your Stocks and Shares ISA. This effectively transfers the assets into the tax-free wrapper, sheltering all future growth and income from HMRC.
The primary driver for this strategy is often Capital Gains Tax (CGT). Each year, you have a CGT allowance, which is the amount of profit you can make from selling assets before any tax is due. According to HMRC’s technical guidance, the CGT allowance is set to be £3,000 for the 2024/25 tax year. A Bed-and-ISA transaction is structured to crystallise a gain that is within this annual allowance. By selling just enough shares to realise a gain of up to £3,000, you pay no CGT. You then use the proceeds (and any new cash to top up your £20,000 ISA allowance) to repurchase the shares inside the ISA.
This is an annual discipline. Executed year after year, it allows you to methodically move a large, unsheltered portfolio into a tax-free environment over time. A case study by HSBC demonstrates the value, showing that moving a £50,000 portfolio via this method can save thousands in CGT over a decade. It is most effective when performed early in the tax year (April/May) to maximise the period of tax-free growth, rather than rushing to meet the March deadline.
It’s important to be aware of the ’30-day rule’ for CGT, which prevents you from selling and repurchasing the same share within 30 days to crystallise a loss. However, this rule does not apply when repurchasing inside an ISA. An interesting alternative is the ‘Bed-and-Spouse’ strategy, where you sell the assets and your spouse immediately repurchases them, which also navigates the 30-day rule and allows you to utilise two sets of allowances. While a Bed-and-SIPP offers greater upfront tax relief, it locks the funds away until retirement, making Bed-and-ISA the preferred choice for those who need access to their capital.
By treating the Bed-and-ISA as an annual financial health check rather than a one-off trick, you can systematically build a completely tax-proof investment portfolio over the long term.
Funding Retirement Basics: The Tactic Using Top UK Dividend Aristocrat Stocks
When planning for retirement, generating a reliable, inflation-proof income stream is the primary objective. While annuities offer a guaranteed income for life, they often lack flexibility and provide no capital for inheritance. A compelling alternative for many is building a portfolio of UK Dividend Aristocrats—companies with a proven, multi-decade track record of consistently increasing their dividend payments.
This strategy is fundamentally about prioritising quality and reliability over speculative high yields. Dividend Aristocrats are typically mature, financially robust companies (often blue-chips found in the FTSE 100) that have demonstrated an ability to grow their earnings and shareholder returns through various economic cycles. The income they provide is not static; its inherent annual growth provides a natural hedge against inflation, helping to preserve your purchasing power throughout retirement. This is a key advantage over a standard fixed annuity, where the income received buys less and less each year.
From a tax and flexibility perspective, a portfolio of dividend-paying shares offers significant advantages. You retain full control and access to your capital, can adjust your holdings as your circumstances change, and the entire portfolio can be passed on to your heirs. The income itself is subject to the more favourable dividend tax rates and can be managed using the strategies discussed throughout this guide, such as utilising allowances and tax wrappers.
The table below compares the key features of a Dividend Aristocrat portfolio against a typical annuity, highlighting the trade-offs between security and flexibility.
| Factor | Dividend Aristocrat Portfolio | Annuity |
|---|---|---|
| Inflation Protection | Natural growth through dividend increases | Fixed unless inflation-linked (expensive) |
| Income Flexibility | Can adjust holdings, reinvest | Fixed for life |
| Capital Access | Full access to capital | No capital return |
| Inheritance | Full portfolio passes to heirs | Nothing (unless joint/guaranteed) |
| Risk Level | Market and dividend cut risk | Provider default risk only |
While this approach carries market risk that an annuity avoids, the combination of a growing income stream, capital preservation, and tax flexibility makes a portfolio of high-quality dividend stocks a cornerstone of modern retirement planning for many UK investors.
Key Takeaways
- Prioritise Your ISA: The most critical action is to use your ISA allowance to shield your most tax-inefficient assets first, such as UK REITs and high-yield bonds.
- Formalise Income Splitting: Don’t just informally share assets with your spouse. Use a Declaration of Trust and Form 17 to legally and effectively double your household’s Dividend Allowance.
- Differentiate Yield from Trap: A dividend yield over 10% is often a warning sign. Focus on dividend sustainability by checking metrics like dividend cover and free cash flow payout.
How to Legally Shield Your Investments From the 24% UK Capital Gains Tax?
While this guide has focused heavily on dividend tax, a holistic approach to investment tax planning must also incorporate strategies to mitigate Capital Gains Tax (CGT). CGT is levied on the profit you make when you sell (or ‘dispose of’) an asset that has increased in value. For higher-rate taxpayers selling residential property, the rate can be as high as 24%, making it a significant consideration for any long-term investor.
The good news is that there is a comprehensive toolkit of legal strategies available to shield your investments from CGT. These are not loopholes but rather government-approved allowances and structures designed to encourage saving and investment. The key is to use them proactively and in combination, rather than waiting until a large, taxable gain has already crystallised. The foundation of any CGT-shielding strategy is, once again, the Stocks and Shares ISA. Any asset held within an ISA is completely exempt from CGT, no matter how large the gain.
Beyond the ISA, the annual CGT exemption is your next line of defence. This allows you to realise a certain amount of gains each year tax-free. By strategically selling small portions of your holdings annually—a process known as ‘tax harvesting’—you can re-base your cost basis and reduce future tax liabilities. Furthermore, assets can be transferred between spouses or civil partners without triggering a CGT event. This allows you to utilise both partners’ annual exemptions and potentially realise gains at a lower tax rate if one partner is a basic-rate taxpayer.
For those with a higher risk tolerance, venture capital schemes like the Enterprise Investment Scheme (EIS) and Venture Capital Trusts (VCTs) offer significant tax incentives, including CGT-free disposal after a qualifying period. These strategies, combined with the ability to offset gains with losses, form a powerful defence against capital gains tax.
Your Toolkit: Advanced CGT Shielding Strategies
- Maximise ISA Allowance: Contribute the full £20,000 annually to permanently shield all future income and gains on those assets.
- Use Annual CGT Exemption: Proactively ‘harvest’ gains up to the £3,000 annual limit each tax year to realise profits tax-free.
- Gift Assets to a Spouse: Transfer assets to your spouse or civil partner before a sale to utilise their CGT allowance and potentially a lower tax band.
- Carry Forward Losses: Remember that losses from previous tax years can be carried forward indefinitely and used to offset gains in the current year.
- Time Disposals Strategically: If you have a very large gain to realise, consider spreading the disposal across two tax years to use two sets of annual exemptions.
To effectively implement these strategies, the next logical step is to conduct a full audit of your current portfolio against this tax-efficiency framework. Start today by identifying your most tax-inefficient holdings and planning their migration into the appropriate tax wrappers.
Frequently Asked Questions About UK Dividend Tax
Which date determines the tax year – ex-dividend or payment date?
The payment date determines which tax year the dividend falls into for UK tax purposes, not the ex-dividend date.
Do I need to declare ISA dividends?
No, dividends from shares held in ISAs are completely tax-free and don’t need to be declared.
What if my only income is £3,000 in dividends?
You likely won’t owe tax as this would be covered by your Personal Allowance (assuming it’s available). However, as it is over the £500 Dividend Allowance, you may still need to inform HMRC, even if no tax is due.