Building financial resilience in the UK isn’t about earning more; it’s about making surgically precise decisions that leverage the unique rules of the British financial system.
- Prioritising guaranteed 25% returns from a Lifetime ISA (LISA) is often smarter than overpaying student loans, which act more like a graduate tax.
- Automating your savings into separate digital ‘pots’ before you can spend the money is the key to building wealth without feeling restricted.
Recommendation: Immediately calculate your 6-month ‘core survival figure’ and start automating at least 15% of your income towards this and other long-term goals.
For many UK professionals in their twenties, the financial script feels pre-written and deeply frustrating. You secure a good job, your salary climbs past £30,000, yet you remain stuck in a cycle of living paycheck to paycheck. The conventional advice—’save 10%’, ‘cut back on lattes’, ‘create a strict budget’—feels both patronising and ineffective against the tide of high rent, stagnant wages, and the looming figure of student debt.
Many financial guides offer generic rules that ignore the unique landscape of UK finance. They’ll tell you to pay down all debt aggressively, failing to differentiate between a 22% APR credit card and a Plan 2 student loan that might be written off. They preach relentless budgeting, a chore that often fails within weeks. But what if the path to financial autonomy wasn’t about more discipline or higher earnings, but about a smarter, more strategic approach?
This guide moves beyond the platitudes. Its purpose is to equip you with a new framework for thinking about your money, one based on understanding and ‘gaming’ the systems available to you. We will explore the specific financial leverage points, from ISA bonuses to Open Banking apps, that can build you a truly resilient financial foundation. We will deconstruct the myth that a higher salary automatically leads to security and provide a clear, automated architecture for your cash flow. This is not about restriction; it is about building a system that generates wealth for you, automatically and intelligently.
This article will provide a clear roadmap for achieving financial stability. Below is a summary of the key strategies we will cover to help you build a solid financial base before you turn 30.
Contents: A Strategic Guide to Your Financial Foundation
- What Are the 3 Essential Financial Metrics Every Professional Must Hit by Age 30?
- Pay Off Student Debt or Start Saving: When Should You Prioritise Each Step?
- Why Earning £60,000 a Year Does Not Guarantee Financial Security in London?
- How to Automate Your Monthly Savings Without Feeling Financially Restricted?
- The Lifestyle Creep Mistake That Traps High Earners in Permanent Debt
- How to Calculate Your Exact Core Survival Figure for a 6-Month Emergency Buffer?
- Why Delaying Your ISA Contributions by 5 Years Costs You £100,000 Ultimately?
- How to Use Open Banking Apps to Optimise Your Daily Household Cash Flow?
What Are the 3 Essential Financial Metrics Every Professional Must Hit by Age 30?
To build a resilient financial foundation, you must stop guessing and start measuring. Forget vague goals like ‘save more’. Instead, focus on three critical metrics that provide a clear snapshot of your financial health. The first is your Emergency Fund Coverage, measured in months. This is your primary shield against life’s uncertainties. The second is your Net Savings Rate, the percentage of your take-home pay you are actively directing towards wealth-building goals. Aiming for 15-20% is a strong target. The third, and most telling, is your Net Worth Trajectory. This is the simple calculation of your assets (cash, investments) minus your liabilities (credit card debt, personal loans). While student debt is a liability, its unique nature in the UK—with many students graduating with an average of £53,000—means we should often view it separately when tracking monthly progress.
Tracking these three figures on a quarterly basis transforms your financial journey from a source of anxiety into a manageable project. It allows you to see real progress, identify where you’re falling short, and make targeted adjustments. For example, if your Net Savings Rate is low despite a good salary, it points directly to an issue with cash flow or lifestyle creep, which we’ll address later. A stagnant Net Worth, even with savings, might indicate your money is sitting in a low-interest account being eroded by inflation. These metrics are your personal dashboard, guiding you from financial uncertainty to deliberate, strategic control.
Pay Off Student Debt or Start Saving: When Should You Prioritise Each Step?
This is the most common and critical question for UK graduates, and the generic answer— »pay off your debt »—is often wrong. The key is to understand that not all debt is created equal. High-interest commercial debt, like credit cards and store finance, is a financial emergency. It must be eliminated with aggressive prejudice. However, UK Student Loans (Plan 2, 3, or 5) are a completely different beast. They function less like a traditional loan and more like a 30-year graduate tax, calculated as 9% of your earnings above a certain threshold.
The concept of « system-gaming » is crucial here. Overpaying a Plan 2 student loan when you’re earning £40,000 is often a poor financial decision. That extra money could instead be channelled into a Lifetime ISA (LISA), where the government gives you a guaranteed, instant 25% bonus. This is a risk-free return that no student loan overpayment can match. For most graduates, the smarter strategy is to pay the mandatory minimum on your student loan and focus all surplus cash on first eliminating high-interest debt, then building an emergency fund, and finally, maximising government-backed investment vehicles like a LISA or pension.
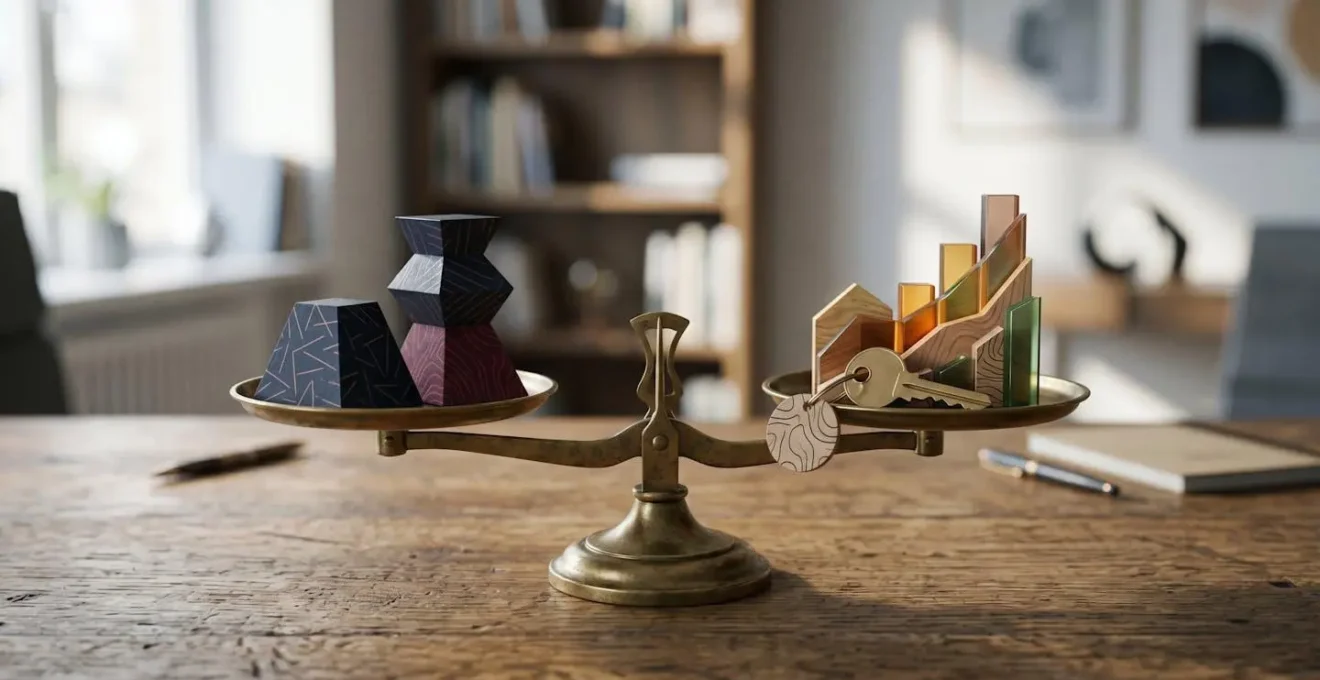
The visual metaphor of a scale helps to clarify this hierarchy. On one side, you have the urgent weight of high-interest debt. On the other, the powerful long-term growth from savings and investments. The student loan sits in the middle, a consistent but manageable deduction, not an emergency to be tackled at the expense of your future wealth.
Case Study: LISA vs. Student Loan Overpayment
A 25-year-old contributing £4,000 annually to a Lifetime ISA receives a guaranteed 25% government bonus (£1,000 per year). Meanwhile, their Plan 2 student loan only requires payments of 9% on income over £27,295. For most graduates earning under £50,000, maximising the LISA bonus provides far better returns than overpaying a student loan that may never be fully repaid before the 30-year write-off period.
The following table, based on an analysis by the UK Parliament library, starkly illustrates the difference in priority between various types of UK debt.
| Debt Type | Interest Rate | Repayment Terms | Priority Level |
|---|---|---|---|
| Credit Cards | 21.7% APR average | Minimum 1-3% monthly | Urgent – Pay First |
| Plan 2 Student Loan | 7.3% (RPI+3%) | 9% over £27,295 | Low – Pay Minimum |
| Plan 5 Student Loan | 3.2% (RPI+0%) | 9% over £25,000 | Low – Pay Minimum |
| LISA Contribution | 25% instant bonus | £4,000 max/year | High – Maximise |
Why Earning £60,000 a Year Does Not Guarantee Financial Security in London?
The « London Paradox » is a trap that ensnares countless ambitious professionals. A £60,000 salary sounds substantial, and it is. However, in the capital, it often fails to translate into financial security or wealth accumulation. The primary reason is that essential costs, particularly housing, rise disproportionately faster than wages. Your gross income might be 30% higher than in another major city, but if your rent is 80% higher, your disposable income—the money you can actually use to build wealth—is significantly lower.
This disparity creates a dangerous illusion of wealth. You might feel « rich » on paper, leading to spending habits that your net income simply cannot sustain. Data confirms this phenomenon; according to one analysis, the average London professional on £60,000 spends approximately 40% of their take-home pay on rent alone, compared to just 25% in a city like Manchester. This leaves a much smaller margin for savings, investing, and building your emergency fund. Financial resilience is not about your gross salary; it is about the gap between your income and your essential expenses. Unless you consciously control your « big ticket » items like housing and transport, a high London salary can paradoxically lead to greater financial fragility than a more modest salary elsewhere.
How to Automate Your Monthly Savings Without Feeling Financially Restricted?
The single most effective strategy for building wealth is to remove yourself from the equation. The traditional method of « spending what’s left after saving » is flawed because it relies on willpower, which is a finite resource. The solution is to design a ‘Cash Flow Architecture’ that automatically diverts money to your financial goals the moment you get paid. This is the principle of « paying yourself first, » supercharged by modern fintech.
Using digital banking apps like Monzo, Starling, or Revolut, you can create a system of pots or vaults for each of your goals: Emergency Fund, LISA, Holiday, etc. On payday, set up automated standing orders to move specific amounts into each pot. This money is now psychologically ‘spent’ on your future. The amount remaining in your main account is what you have for guilt-free discretionary spending for the rest of the month. You are no longer saving; you have simply engineered your finances so that wealth accumulation happens in the background. This approach completely removes the feeling of restriction, as you are free to spend 100% of the money you see in your « spending » account.
Case Study: The Monzo Pots Automation Strategy
A 28-year-old consultant automated their £3,500 monthly salary using Monzo’s features. On payday: £1,400 was moved to a ‘Bills Pot’, £700 to an ‘ISA Investment Pot’, £400 to a ‘LISA Pot’, and £600 to an ‘Emergency Fund’ until it reached a £5,000 target. This left £400 for guilt-free spending. After six months, they had saved £7,200 without ever feeling like they were on a budget, as the money was moved before they had a chance to spend it.
Many UK fintech apps have built-in features to make this even easier, gamifying the process of saving. Here’s a comparison based on data from MoneyHelper and app features.
| App | Gamification Feature | Typical Monthly Savings | Best For |
|---|---|---|---|
| Plum | Rainy Day Rule (saves when raining) | £50-200 automated | Weather-triggered savers |
| Moneybox | Round-ups + weekly deposits | £30-150 from round-ups | Passive micro-investors |
| Chip | AI-powered auto-saves | £100-400 AI-calculated | Hands-off savers |
| Emma | Subscription cancellation tracker | £50-150 from cancelled subs | Subscription auditors |
The Lifestyle Creep Mistake That Traps High Earners in Permanent Debt
Lifestyle creep is the silent wealth killer. It’s the insidious tendency to increase your spending as your income grows, ensuring you never actually get ahead. A promotion or pay rise feels like a victory, but without a plan, that extra income is quickly absorbed by small, almost unnoticeable upgrades: a nicer flat, more expensive takeaways, premium brand groceries, a better car. Suddenly, you’re earning 30% more but your savings rate is the same, or even lower. You are running faster, but staying in the same place financially.
The key to defeating lifestyle creep is to be proactive, not reactive. You must have a pre-defined plan for any new income *before* it hits your bank account. A powerful and balanced approach is the 50-30-20 Pay Rise Allocation Framework. This rule dictates how you should immediately allocate any increase in your monthly take-home pay. By systematically funnelling the majority of your raise into wealth-building and specific goals, you capture the financial benefit of your hard work before it can be frittered away. Crucially, by also allocating a portion to lifestyle upgrades, you avoid feeling deprived, making the plan sustainable long-term.
Case Study: From Aldi to Waitrose, A Lifestyle Inflation Story
A Manchester couple, each earning £35,000, received promotions. They instinctively upgraded their lifestyle, switching their weekly shop from Aldi (£60) to Waitrose (£140), moving from a £900/month flat to a £1,600/month apartment, and swapping Ryanair city breaks for long-haul flights. Despite their combined income increasing by over 30%, they were saving less than before their raises, a classic example of how lifestyle creep consumed their entire pay increase.
To avoid this trap, implement this framework within 48 hours of being notified of a pay rise:
- 50% to Wealth Building: The first half of your raise should immediately go towards your future self. Increase your pension contributions by 25% of the raise, and boost your ISA investments by the other 25%.
- 30% to Specific Goals: Use this portion to accelerate a specific, tangible goal. This could be overpaying your mortgage, building a house deposit fund, or aggressively eliminating any remaining high-interest debt.
- 20% to Lifestyle Upgrades: This is the ‘guilt-free’ portion. Allow yourself a measured improvement in your standard of living. This prevents the feeling of deprivation and makes your financial plan sustainable.
How to Calculate Your Exact Core Survival Figure for a 6-Month Emergency Buffer?
Your emergency fund is the absolute cornerstone of your financial foundation. It’s the buffer that allows you to take calculated risks, navigate job losses, and handle unexpected crises without derailing your life or going into debt. The common advice is « save 3-6 months of expenses, » but what does that actually mean? To make it tangible, you need to calculate your ‘Core Survival Figure’—the absolute minimum you need to live on for one month if your income disappeared tomorrow.
This is not your current monthly spending. It is a stripped-back figure that covers only the true essentials. To calculate it, you must go through your bank statements and identify every cost that is non-negotiable for survival and basic well-being. This includes rent/mortgage, council tax, utilities, essential food and transport, and insurance premiums. It’s also wise to include a small, non-zero budget for social activities to prevent total isolation during a period of unemployment, which is critical for mental health. Once you have this monthly total, multiply it by 6 to get your full emergency fund target. This figure, which could be anywhere from £10,000 to £20,000 depending on your circumstances, is your first and most important financial goal.
Your Action Plan: Calculate Your UK Emergency Costs
- Fixed Costs: List your non-negotiable monthly outgoings. This includes Rent/Mortgage, Council Tax (typically £100-400/month), essential utilities (£150-250), and any insurance policies you hold.
- Variable Essentials: Go through your last 3 months of spending. Calculate your average monthly spend on ‘essentials only’ for food (£200-300), essential transport to find work, and your phone/broadband contract.
- Forgotten Expenses: Identify annual or irregular costs and provision for them monthly. This includes your MOT/car service (£500/year ÷ 12), TV Licence (£13/month), and a realistic allowance for dental/optical check-ups.
- Wellbeing Minimum: Allocate a small, non-negotiable budget for basic social contact (£50-100/month). This is crucial to prevent isolation and maintain mental health during a stressful period like unemployment.
- Total & Multiply: Sum up all these monthly figures to get your ‘Core Survival’ number. Multiply this by 6 to determine your final Emergency Fund target.
This fund should be kept in a high-interest, easy-access savings account or similar liquid vehicle. It is not an investment; its return is the peace of mind and security it provides. In the current UK market, high-interest easy-access accounts offer 3.75-4.5% returns, which helps your fund retain its value against inflation while remaining instantly accessible.
Key Takeaways
- Financial resilience in the UK is built by strategically using system-specific advantages like ISA bonuses, not just by earning more.
- Differentiate debt: aggressively pay off high-interest credit cards, but treat student loans as a long-term graduate tax, prioritising saving and investing instead of overpaying.
- Automate your savings using fintech apps to build wealth effortlessly, and create a pre-emptive plan to allocate any pay rises before lifestyle creep consumes them.
Why Delaying Your ISA Contributions by 5 Years Costs You £100,000 Ultimately?
The most powerful force in finance is compound interest, and its fuel is time. Delaying the start of your investment journey, even by a few years, has a devastatingly large impact on your ultimate wealth, far greater than most people imagine. The years between 25 and 30 are the most valuable investing years of your life, because every pound invested has the longest possible time to grow.
Consider the Lifetime ISA (LISA). If you open one at 25 and contribute the maximum £4,000 a year, you receive a £1,000 government bonus each year. By age 30, you’ve received £5,000 in free money, plus the compound growth on top. Someone who starts at 30 has permanently missed out on that £5,000 bonus and its subsequent growth. Over a working life, this small head start can compound into a difference of over £100,000 by retirement. The initial contributions do the heaviest lifting over the long term.
Case Study: The Tale of Two LISA Timelines
Person A opens a LISA at 25, contributing £4,000 annually. By age 30, with the 25% government bonus each year and modest 4% annual returns, their pot is worth over £27,000. Person B, who starts at 30, has zero. That £27,000 head start, left to compound over the next 30 years, is what creates a six-figure difference in their final retirement pots by age 60.
This effect is not limited to LISAs. The same principle applies to a Stocks & Shares ISA. Due to the power of compounding, the timing of your investment matters more than the amount. For example, analysis shows that £20,000 invested in a global tracker fund between ages 25-30 can grow to £82,000 by age 60 (assuming 7% average returns). In contrast, a larger contribution of £30,000 invested ten years later between ages 35-40 would only reach £73,000 by the same age. Starting early is the single greatest financial leverage point you have.
How to Use Open Banking Apps to Optimise Your Daily Household Cash Flow?
While automating your savings sets your long-term strategy, optimising your daily cash flow is where you can unlock hundreds, if not thousands, of pounds per year. This is where Open Banking apps like Emma, Snoop, and Plum come into their own. By securely connecting to all your UK bank accounts and credit cards, these apps provide a unified dashboard of your entire financial life, identifying patterns and wastage that are impossible to spot manually.
Their most powerful feature is the ability to conduct a ‘Subscription Autopsy’. These apps automatically scan your transactions and list all your recurring payments, from Netflix and Spotify to that forgotten gym membership. This simple list is often a moment of shocking clarity. You can then systematically triage each subscription: Keep, Downgrade (e.g., from 4K to a standard plan), or Cut. This exercise alone can easily save you £50-£100 per month. Beyond subscriptions, these apps use their overview of your spending to proactively alert you to better deals on major bills like energy, broadband, and insurance just before your contract auto-renews at a higher price, turning passive bill-paying into active money-saving.
Case Study: Open Banking Bill-Switching Success
A Birmingham household using the Snoop app saved £1,200 annually. The app’s proactive alerts, triggered by Open Banking data, notified them just before their contracts were due for auto-renewal. They switched their energy provider (saving £400), broadband (£300), mobile contracts for two phones (£360), and home insurance (£140). This saving was achieved without any manual tracking or spreadsheet management, simply by responding to the app’s notifications.
Here is a simple framework for using an app like Emma to take control:
- Connect Everything: Link all your UK bank accounts and credit cards to the app via its secure Open Banking connection.
- Run the Audit: Use the ‘Find Subscriptions’ or ‘Recurring Payments’ feature to generate a complete list.
- Triage and Act: Go through the list and make immediate decisions. Cancel unused services directly. A forgotten £40/month gym membership is a £480/year saving.
- Set Up Alerts: Enable ‘Wastage Alerts’ or ‘Bill Reminders’ to ensure the app notifies you of upcoming renewals and unused subscriptions in the future.
By leveraging these tools, you transform your smartphone into a personal finance manager that actively works to keep more money in your pocket, optimising the cash flow you need to fuel your savings and investment goals.
Building a resilient financial foundation is not a one-time event but a system you design and implement. By moving beyond generic advice and embracing strategies tailored to the UK financial landscape—from understanding the true nature of student debt to leveraging ISA bonuses and automating your cash flow—you can break the paycheck-to-paycheck cycle. The key is to take control, make deliberate choices, and build an architecture that makes your money work for you. To put these strategies into practice, the logical next step is a personalised assessment of your own financial situation. Evaluate your current savings rate, debt structure, and spending habits today to identify the most impactful change you can make this month.