Integrating alternatives is not about chasing trends, but about building a resilient ‘core-satellite’ portfolio structure around your traditional holdings.
- Utilise UK-specific tax wrappers like ISAs and EIS/SEIS to maximise the efficiency of each asset class.
- Actively budget for illiquidity as a strategic choice rather than simply fearing it as a passive risk.
Recommendation: Begin by assessing your risk profile to allocate 10-20% of your total portfolio to a diversified ‘satellite’ of alternative assets.
For many high-income earners in the UK, the financial journey follows a familiar path. You’ve diligently maxed out your ISA contributions, built a solid pension, and perhaps invested in a standard portfolio of equities and bonds. Yet, with cash yields eroded by inflation and public markets exhibiting unnerving volatility, the question of « what’s next? » becomes increasingly urgent. You see headlines about art, fine wine, and private equity delivering impressive returns, but the path to entry seems opaque, complex, and fraught with risk.
The conventional advice is often a simple, unhelpful platitude: « diversify into alternatives. » This usually comes with a laundry list of exotic assets, leaving you to navigate a world of specialist dealers and high minimum investments alone. It frames alternative investing as a speculative leap of faith, a world apart from the structured, regulated environment of your Stocks & Shares ISA. This perception creates a barrier, preventing sophisticated investors from accessing powerful tools for wealth preservation and growth.
But what if the true key to success wasn’t in picking a single winning asset, but in adopting a new structural framework? The most effective approach is to view your portfolio through a ‘Core-Satellite’ model. Your ISA, pension, and other traditional investments form the stable, liquid ‘core’. Alternative assets then become tactical ‘satellites’—smaller, targeted allocations designed to achieve specific goals like inflation hedging, capturing high growth, or generating uncorrelated returns. This isn’t about speculation; it’s about strategic construction.
This guide will provide a practical methodology for building that satellite portfolio. We will deconstruct how to choose assets based on their specific characteristics, how to gain access to private markets with modest capital, how to manage the critical factor of illiquidity, and how new technologies like tokenization are making it all more accessible than ever before. It’s time to move beyond the simple ‘what’ and master the strategic ‘how’.
To navigate this landscape effectively, this article breaks down the core strategies and asset classes available to UK investors. The following sections provide a clear roadmap for building a robust and diversified portfolio that goes beyond traditional stocks and bonds.
Summary: A Strategic Approach to Alternative Investments in the UK
- Physical Gold vs Fine Wine: Which Alternative Asset Hedges UK Inflation Better?
- How to Invest in UK Private Equity Safely With Only £5,000 Initial Capital?
- The Illiquidity Trap That Freezes Your Capital in Unsellable Alternative Assets
- Balancing Extremes: The Method to Mix Crypto Volatility With Government Bond Stability
- Why Alternative Asset Classes Are No Longer Exclusively Reserved for Billionaires?
- Why Tokenized Property Allows You to Build a Real Estate Portfolio With Only £100?
- Adding Defensive Commodities: The Tactic to Protect Assets Against High Inflation
- How to Diversify Your Portfolio Using Tokenized Real-World Assets?
Physical Gold vs Fine Wine: Which Alternative Asset Hedges UK Inflation Better?
The first port of call for many investors seeking refuge from inflation is physical gold. Its reputation as a store of value is centuries old, a tangible hedge against currency debasement. However, assuming it’s the only or best option is a strategic error. The world of alternatives offers more nuanced tools. Fine wine, for instance, presents a compelling and often superior inflation hedge due to its unique supply-and-demand dynamics. As a bottle ages, its quality can improve while its supply simultaneously dwindles as other bottles are consumed, creating inherent scarcity that gold does not possess.
This is not just theoretical. During recent periods of high inflation, the performance differential has been stark. Analysis from the fine wine exchange Liv-ex revealed that during 2021, a year of rising inflation, fine wine indices delivered remarkable growth. For example, some market segments saw 19.08% fine wine returns while gold posted negative returns during the same period. This highlights a crucial principle: not all « real assets » behave identically. While gold is driven by macroeconomic sentiment and currency fluctuations, fine wine is also influenced by consumption, rarity, and critical acclaim.
Therefore, when building a satellite portfolio, the choice between gold and wine is not an « either/or » decision but a strategic one based on your specific objectives. Gold may offer a broad hedge against systemic financial risk, but fine wine can provide a more direct and potent hedge against consumer price inflation, as luxury goods prices often rise with it. Understanding these subtleties is the first step toward constructing an intelligent and effective alternative asset allocation. The goal is not to find the single « best » asset, but to blend assets whose characteristics best match the risks you aim to mitigate.
How to Invest in UK Private Equity Safely With Only £5,000 Initial Capital?
Private Equity (PE) and Venture Capital (VC) have long been the preserve of institutional investors and the ultra-wealthy, promising outsized returns from investing in the next generation of innovative companies. The perception of million-pound minimums and exclusive Mayfair funds has kept the average high-income earner on the sidelines. However, the UK government has created powerful, tax-efficient frameworks that open the door to this asset class for a much broader audience: the Enterprise Investment Scheme (EIS) and the Seed Enterprise Investment Scheme (SEIS).
These schemes are designed to encourage investment in early-stage, high-growth companies by providing significant tax reliefs that dramatically de-risk the investment. For an investor, this changes the entire risk/reward calculation. For instance, EIS offers 30% income tax relief on the amount invested, meaning a £5,000 investment only exposes £3,500 of your capital from day one. SEIS goes even further, offering up to 50% relief. Furthermore, any gains are Capital Gains Tax (CGT) free if held for a minimum period, and crucially, if the investment fails, you can claim loss relief against your income tax, further cushioning the downside.
This structure makes it possible to build a diversified portfolio of startups with a relatively small amount of capital. Platforms like Crowdcube and Seedrs have democratised access, allowing you to invest as little as a few hundred pounds into multiple ventures. This diversification is key to mitigating the high failure rate inherent in early-stage investing.
Your Action Plan: Investing in UK Startups via EIS/SEIS
- Understand Tax Reliefs: Familiarise yourself with the key benefits. EIS provides 30% income tax relief, while SEIS offers a substantial 50% relief on qualifying investments.
- Calculate Your True Risk: On a £5,000 EIS investment, the 30% tax relief immediately reduces your at-risk capital to just £3,500. Calculate this for every potential investment.
- Diversify Widely: Do not put all your capital into one startup. Use platforms like Crowdcube to spread a £5,000 allocation across 10-15 different companies with low minimums.
- Focus on Loss Relief: Understand that if an investment results in a loss, you can offset this against your income tax bill, providing a significant safety net.
- Plan for the Long Term: To retain all tax benefits, you must hold the investment for a minimum of three years. This is not a liquid, short-term strategy.
The Illiquidity Trap That Freezes Your Capital in Unsellable Alternative Assets
The single greatest risk in alternative investing isn’t necessarily losing money—it’s losing access to it. This is the illiquidity trap: a situation where your capital is locked into an asset that you cannot sell quickly or at a fair price when you need the funds. This is a fundamental departure from public markets, where stocks and bonds can be sold in seconds. Forgetting this distinction is one of the most common and costly mistakes an investor can make. Many alternatives, from venture capital to direct property, can have lock-in periods stretching from 5 to 10 years or more, with no guarantee of an exit.
However, framing liquidity as a simple binary—liquid vs. illiquid—is misleading. A more sophisticated approach is to view it as a spectrum and to practice what we can call ‘liquidity budgeting’. This means consciously deciding what portion of your net worth you can afford to have locked away for the medium to long term in exchange for a potential ‘illiquidity premium’—the higher returns often offered by less liquid assets. You wouldn’t use your emergency fund to buy a piece of art, but allocating a portion of your long-term growth portfolio is a different matter.
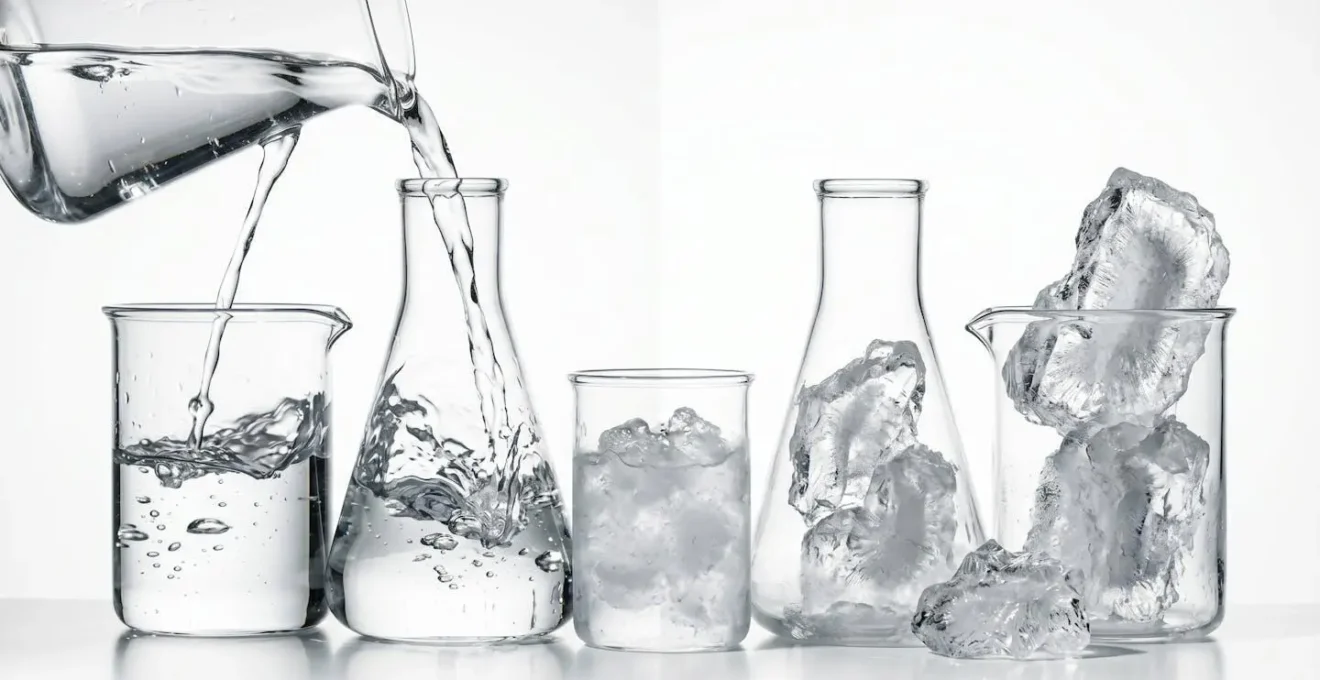
As the visual metaphor above suggests, your financial assets can range from flowing water (cash, listed stocks) to solid ice (direct VC, private art). Your job as a portfolio architect is to decide on the right mix. This requires understanding the typical lock-in periods and exit options for each asset class, which can vary dramatically. Listed infrastructure funds might trade daily, while selling a stake in a crowdfunded startup can take years and depend on a future acquisition or IPO.
The following table provides a clear overview of the liquidity spectrum across common UK alternative assets, forming the basis for your liquidity budget.
| Asset Class | Typical Lock-in Period | Exit Options | Liquidity Risk |
|---|---|---|---|
| Listed Infrastructure Funds | Daily liquidity | Stock exchange trading | Low |
| Fine Wine (in bond) | Weeks to months | Specialist dealers/auctions | Medium |
| Crowdfunded Equity | 3-7 years | Secondary markets (limited) | High |
| Direct Venture Capital | 5-10+ years | Exit events only | Very High |
Balancing Extremes: The Method to Mix Crypto Volatility With Government Bond Stability
The Core-Satellite model truly demonstrates its power when managing assets at the opposite ends of the risk spectrum, such as cryptocurrencies and government bonds (Gilts in the UK). Crypto offers the potential for explosive, asymmetric returns but comes with extreme volatility. Gilts, on the other hand, provide stability and predictable income but with modest growth prospects. Attempting to hold both without a clear strategy can lead to a disjointed portfolio. The key is to use the UK’s tax-wrapper system to house each asset in the optimal environment—a concept we can call ‘tax-wrapper arbitrage’.
Your Stocks & Shares ISA is the ideal home for your ‘core’ stable assets like bonds or bond funds. All income and capital gains within an ISA are completely tax-free. Placing your low-to-medium return assets here ensures that every bit of growth is yours to keep. Conversely, holding a highly volatile asset like Bitcoin in an ISA could be a waste of your valuable allowance if the price crashes, and it offers no mechanism to offset losses. Instead, crypto is often better suited to a General Investment Account (GIA). This allows you to utilise your annual CGT allowance (£6,000 for 2023/24, reducing to £3,000 for 2024/25) to realise gains tax-efficiently through a process known as ‘harvesting’.
A disciplined rebalancing strategy is crucial. This isn’t about market timing, but about managing risk. A common method is to set a volatility threshold. For instance:
- Allocate your core bond holdings to your Stocks & Shares ISA to ensure all income and gains are tax-free.
- Hold your satellite crypto assets in a General Investment Account (GIA) to strategically utilise your annual CGT allowance.
- Establish a strict rebalancing rule: for example, if crypto grows to exceed 5% of your total portfolio value, trim the profits back down to a 2% allocation.
- Reinvest those harvested crypto profits into your stable core, such as by purchasing more UK Gilts or a bond fund within your ISA wrapper.
- Review your portfolio quarterly, but only rebalance based on these threshold rules, not arbitrary calendar dates.
This systematic approach turns volatility from a threat into an opportunity, allowing you to methodically skim profits from your high-risk satellite and compound them in your tax-free core. Financial advisors often suggest a 10-20% portfolio allocation to alternatives is generally suggested by financial advisors for diversification, and this method provides a structured way to manage that allocation.
Why Alternative Asset Classes Are No Longer Exclusively Reserved for Billionaires?
The landscape of alternative investing has undergone a radical transformation over the past decade. The idea that you need to be a certified high-net-worth individual with millions to invest is an outdated notion. This shift has been driven by two primary forces: technological innovation and regulatory evolution. Technology, through platforms and tokenization, has created the tools for fractional ownership, while regulators, like the UK’s Financial Conduct Authority (FCA), have established frameworks to allow retail and sophisticated investors safer access to these markets.
This democratization is not just about lower investment minimums; it’s about a fundamental change in access, transparency, and fee structures. Where once a private equity investment required a direct relationship with a fund and a seven-figure cheque, today’s investor can build a diversified venture portfolio on a platform like Seedrs for a few thousand pounds. Similarly, owning a share of a case of investment-grade Bordeaux no longer requires buying the entire case at auction; it can be done fractionally for £100.
This new paradigm allows for the construction of a far more granular and diversified satellite portfolio. An investor can now gain exposure to venture capital, fine wine, and commercial property simultaneously, with allocations that would have been impossibly small a decade ago. The table below starkly illustrates this shift, comparing the old, exclusive world with the new, accessible one.
| Aspect | Before (Pre-2010) | Today |
|---|---|---|
| Minimum PE Investment | £1M+ for Mayfair funds | £100 on Seedrs/Crowdcube |
| Access Requirements | Certified high-net-worth only | Restricted/sophisticated investor category |
| Fee Structure | 2% management + 20% performance | Platform fees 1-2% + success fees |
| Wine Investment | Full case purchases | £100 fractional ownership |
Why Tokenized Property Allows You to Build a Real Estate Portfolio With Only £100?
For most UK residents, direct property ownership is the most familiar « alternative » investment. However, the barrier to entry for buy-to-let has become prohibitively high. Soaring property prices, combined with significant upfront costs, have pushed it out of reach for many. Tokenization directly addresses this challenge, offering a revolutionary way to gain exposure to the property market without the traditional hurdles. It enables fractional ownership, allowing you to buy a small piece of a specific property, managed professionally on your behalf.
The mechanics are straightforward: a property is placed into a legal entity, typically a Special Purpose Vehicle (SPV). Ownership of this SPV is then divided into digital tokens, which investors can buy. You own a share in the company that owns the asset, entitling you to a proportional share of any rental income and capital appreciation. This structure bypasses the largest barriers to traditional property investment.
Case Study: UK Buy-to-Let Barriers vs. Tokenization Benefits
Consider the cost of a traditional UK buy-to-let investment. With average property prices around £280,000, a typical 25% mortgage deposit requires £70,000 in upfront capital. On top of this, the 3% Stamp Duty Land Tax (SDLT) surcharge for second homes adds another £8,400, bringing the initial outlay to nearly £80,000 before even considering legal and administrative fees. In stark contrast, tokenization platforms eliminate these barriers entirely. They allow investors to gain fractional ownership in a specific, vetted property with an investment from as little as £100. The property is held within an SPV, meaning investors are shielded from the responsibilities and liabilities of being a landlord, while still gaining direct economic exposure to the UK property market’s returns.
This model fundamentally changes the game for portfolio construction. Instead of concentrating a large sum into a single property, an investor can now spread a much smaller amount of capital across multiple properties in different regions, achieving a level of diversification that was previously impossible for an individual buy-to-let investor. It transforms property from a monolithic, illiquid asset into a granular and accessible component of a satellite portfolio.
Adding Defensive Commodities: The Tactic to Protect Assets Against High Inflation
Alternative assets often behave differently to public market assets like equities and bonds. Their unique characteristics mean they can help investors achieve a diversified portfolio.
– Invesco UK, Alternative Investment Capabilities Report
Commodities—the raw materials that power the global economy, from oil and natural gas to copper and wheat—are a classic defensive play. When inflation rises, the cost of these essential goods is often a primary driver. Holding a broad basket of commodities can therefore provide a direct and effective hedge, as their prices tend to rise with inflation. In the past, gaining this exposure was complex, requiring futures contracts or specialised funds. Today, it can be done with the same ease as buying a stock, directly within your Stocks & Shares ISA.
The key is using Exchange Traded Commodities (ETCs). These are financial instruments that trade on a stock exchange, like the London Stock Exchange (LSE), and are designed to track the price of a single commodity or a broad index of them. By purchasing an ETC, you gain the economic exposure without having to physically store barrels of oil or bushels of wheat. Because they are listed securities, many are fully eligible to be held within an ISA, meaning all gains are completely tax-free.
This allows for highly tactical and personalised inflation hedging. For example:
- Open a Stocks & Shares ISA: Ensure your chosen broker provides access to securities listed on the London Stock Exchange.
- Research Broad ETCs: For general inflation protection, look at broad-basket ETCs like the WisdomTree Broad Commodities (AIGC), which tracks a diverse range of commodities.
- Consider Specific Hedges: For targeted exposure, you can use single-commodity ETCs. For instance, iShares Physical Gold (SGLN) provides a direct link to the gold price.
- Manage Currency Risk: Many commodities are priced in USD. To eliminate currency risk, look for GBP-hedged versions of these ETCs, which neutralise the effect of fluctuations in the GBP/USD exchange rate.
- Match to Personal Exposure: You can even align your commodity holdings to your personal inflation risks. If rising energy bills are a major concern, a small allocation to a Natural Gas ETC can provide a specific hedge.
By using ISA-eligible ETCs, you can build a sophisticated, tax-efficient commodity satellite that acts as a powerful defensive layer for your core portfolio.
Key Takeaways
- The ‘Core-Satellite’ model provides a disciplined structure for integrating alternatives around a stable base of traditional investments like ISAs.
- UK-specific tax wrappers (EIS, SEIS, ISA) are not just a benefit but a central strategic tool for maximising returns and mitigating risk.
- Liquidity is not a binary risk but a spectrum that can be managed through conscious ‘liquidity budgeting’ and appropriate asset selection.
How to Diversify Your Portfolio Using Tokenized Real-World Assets?
Tokenization is not just a niche technology for property; it is a macro trend poised to revolutionise how we own and trade a vast array of real-world assets (RWAs). From fine art and luxury watches to whisky casks and music royalties, any asset with verifiable value can, in theory, be fractionalised and traded via digital tokens. This represents the ultimate evolution of the satellite portfolio, offering unprecedented access to asset classes and a new level of diversification. The global market for alternatives is already enormous, and PwC forecasts for global alternative asset allocation to reach $27.6 trillion by 2028, with tokenization acting as a major catalyst for this growth.
The UK is positioning itself at the forefront of this financial innovation. The Financial Conduct Authority’s Digital Securities Sandbox provides a regulated environment for firms to test these new models under regulatory supervision. This initiative is paving the way for a trusted ecosystem where investors can confidently buy and sell fractional shares of assets that were once the exclusive domain of specialist collectors and funds. It signals a future where an investor’s satellite portfolio could contain a slice of a blue-chip painting, a share in the royalties of a hit song, and a piece of a prime commercial property, all managed from a single digital platform.
This technology solves the two biggest historical problems with alternatives: high minimums and poor liquidity. By dividing an asset into thousands of small-value tokens, it drastically lowers the cost of entry. While secondary markets are still developing, the digital nature of tokens promises to create far more liquid trading environments than the traditional auction house or private dealer model. For the strategic investor, this is the final piece of the puzzle, enabling the construction of a truly diversified, multi-asset class satellite portfolio that can be precisely tailored to their financial goals.
To apply this core-satellite framework effectively, the next logical step is to review your current asset allocation, determine your risk tolerance, and establish a clear ‘liquidity budget’ to guide your first satellite investment.
Frequently Asked Questions on Tokenized Real-World Assets
What exactly do I own with a property token?
You own a share in a UK Special Purpose Vehicle (SPV) that holds the title to the property, not direct ownership of the bricks and mortar. This structure provides legal separation and protects investors, as the asset is ring-fenced from the platform operating it.
Is my tokenized property investment FSCS protected?
No, investments in tokenized property or other real-world assets are typically not covered by the Financial Services Compensation Scheme (FSCS). This is a higher-risk investment, and your capital is at risk, unlike with FSCS-protected bank deposits.
How does this differ from REITs?
Real Estate Investment Trusts (REITs) are publicly traded companies that own and operate a large portfolio of properties. They offer instant liquidity on stock exchanges and broad diversification. In contrast, property tokens provide direct economic exposure to a single, specific property, offering more targeted investment but with significantly more limited liquidity.