
Automating your UK index tracking is less about ‘set-and-forget’ and more about choosing the right automation engine for your goals and portfolio size.
- Robo-advisors enforce discipline and save time, but their percentage-based fees (the ‘convenience tax’) become costly for portfolios over £50k.
- Understanding key details like fee stacking, synthetic ETF risks, and dividend reinvestment is crucial to maximising your automated returns.
Recommendation: Start with a robo-advisor for discipline and simplicity, but plan to migrate to a DIY broker once your portfolio exceeds the £50,000 to £80,000 range to slash costs.
The ambition for many investors is simple: to have their money work for them, quietly and efficiently, in the background. This has made passive index tracking the default strategy for building long-term wealth. The conventional wisdom is to « buy a global tracker, » keep costs low, and stay the course. But in the modern UK investment landscape, the ‘how’ is more complex than the ‘what’. You’re faced with a dizzying array of platforms, from fully managed robo-advisors like Nutmeg to giant DIY platforms like Vanguard.
The typical advice often falls into platitudes about ease of use or low fees. But this overlooks the fundamental choice you’re making. This isn’t just about picking a product; it’s about selecting an automation philosophy. The real question isn’t « which platform is best? » but « which type of automation engine fits my needs, my portfolio size, and my temperament right now? » Viewing these services as different grades of automation allows for a much smarter decision.
This guide reframes the debate. We’ll move beyond surface-level comparisons and analyse these platforms as sophisticated automation tools. We will quantify the real, long-term impact of the « convenience tax »—the fees you pay for hands-off management. We will explore the hidden risks in certain automated products and provide a clear framework for knowing when your own growth demands an upgrade from a managed service to a self-directed approach. It’s time to look under the bonnet of investment automation.
This article will guide you through the critical decisions needed to build and optimise your automated investment strategy. We will break down the options, the costs, the risks, and the clear action steps for every stage of your journey.
Summary: Automating Your UK Index Tracking Strategy
- Nutmeg vs Vanguard: Which Robo-Advisor Offers the Best Automated ETF Tracking?
- How to Build a Globally Diversified ETF Portfolio With Just £100 Monthly?
- Why a 0.5% Difference in ETF Fees Will Cost You £30,000 Over 20 Years?
- The Synthetic ETF Trap That Adds Hidden Counterparty Risks to Your Savings
- When Should You Move Your Tracking Portfolio From a Robo-Advisor to a DIY Broker?
- How to Automate Dividend Reinvestment to Accelerate Your Compound Growth?
- Hedged vs Unhedged Global ETFs: Which Protects Your Portfolio Better Today?
- How to Configure Automated Trading Bots for Consistent Passive Income?
Nutmeg vs Vanguard: Which Robo-Advisor Offers the Best Automated ETF Tracking?
For UK investors seeking automation, Nutmeg and Vanguard represent two dominant but fundamentally different approaches. Understanding this difference is the first step in choosing the right engine. Nutmeg, now owned by JP Morgan, is a pure robo-advisor: a discretionary manager that builds and maintains a portfolio for you. Vanguard UK offers both a managed option and a massive DIY platform, but its core strength lies in its own low-cost funds.
Nutmeg offers a wider range of investment styles and sources its Exchange-Traded Funds (ETFs) from multiple providers to construct its portfolios. This can offer broader diversification. Vanguard’s managed options, like its popular LifeStrategy funds, are a ‘fund-of-funds’ built exclusively from other Vanguard funds. This is simpler and often cheaper, with a 0.15% account fee, but you are locked into the Vanguard ecosystem. In contrast, Nutmeg’s management fees are significantly higher, ranging from 0.45% to 0.75%, a clear example of the ‘convenience tax’ for their hands-off service and wider fund selection.
While Nutmeg boasts a higher-rated app and more hands-on support for larger portfolios, Vanguard’s reputation is built on its rock-solid, low-cost philosophy. This is reflected in user satisfaction; a recent survey found that 97% of Vanguard customers would recommend it, compared to 87% for Nutmeg. The choice boils down to whether you prioritise the curated, multi-provider experience of a premium robo-advisor or the ultra-low-cost, single-provider simplicity of an industry giant.
The following table provides a direct comparison of their key features, helping you weigh the trade-offs between cost, flexibility, and service.
| Feature | Nutmeg (JP Morgan Personal Investing) | Vanguard UK |
|---|---|---|
| Platform Type | Robo-advisor (discretionary manager) | DIY platform + managed option |
| Minimum Investment | £500 (£100 for LISA/JISA) | £500 lump sum or £100/month |
| Management Fee | 0.45% – 0.75% annually | 0.15% account fee (capped at £375) |
| Investment Range | Multi-provider ETF portfolios | 80+ Vanguard-only funds & ETFs |
| Portfolio Options | Fixed, Fully Managed, Smart Alpha, SR | LifeStrategy, Target Retirement funds |
| Human Support | Yes (above £10k) | Educational resources only |
| App Rating | 4.8/5 (18,000 reviews) | 3.8/5 (270 reviews – new app) |
| Assets Under Management | £5.6bn (250,000 investors) | £24bn (640,000 UK customers) |
How to Build a Globally Diversified ETF Portfolio With Just £100 Monthly?
The idea of building a global investment portfolio can seem daunting, but modern platforms have made it remarkably accessible. You don’t need a large lump sum to start; a consistent monthly contribution of just £100 is more than enough to begin compounding wealth. The key is to leverage platforms with low minimums and fractional shares, which allow you to own a piece of an ETF even if you can’t afford a full share.
The first step is choosing the right venue. Many UK robo-advisors are specifically designed for this purpose. Platforms like Wealthify, Moneyfarm, and InvestEngine welcome small, regular investments. In fact, industry data shows that most UK robo-advisors have monthly minimums of just £25-£50, making the £100 threshold easily achievable. Alternatively, DIY platforms like Trading 212 or InvestEngine’s DIY service offer fractional shares, giving you direct control over which ETFs you buy.
Once you’ve chosen a platform, the process is straightforward automation. You’ll complete a risk questionnaire that helps the robo-advisor (or you) determine the right mix of assets, typically equities and bonds, for your timeline and goals. Then, you set up a Direct Debit or standing order for your £100 monthly contribution. This is the core of the automation: it ensures you invest consistently without emotion or procrastination, a practice known as dollar-cost averaging. For a simple DIY approach, a single, globally diversified ETF like VWRP (Vanguard FTSE All-World UCITS ETF) can provide exposure to thousands of companies worldwide, effectively building your global portfolio with one transaction.
Your Action Plan: Starting with £100 a Month
- Choose a Low-Minimum Platform: Select a robo-advisor (e.g., Wealthify, Moneyfarm) or a fractional share broker (e.g., Trading 212, InvestEngine DIY) that accepts £100 monthly contributions.
- Complete the Risk Questionnaire: Honestly answer questions about your goals, timeline, and comfort with risk to establish the correct asset allocation for your portfolio.
- Set Up Automatic Contributions: Establish a monthly Direct Debit for £100. This is the most critical step for building discipline and benefiting from dollar-cost averaging.
- Select Your Portfolio: With a robo-advisor, this is done for you. On a DIY platform, consider starting with one or two broad, all-world ETFs (like VWRP) for maximum diversification with minimum complexity.
- Monitor Annually, Not Daily: Review your portfolio’s performance once a year to ensure it still aligns with your goals. Avoid the temptation to react to short-term market noise.
Why a 0.5% Difference in ETF Fees Will Cost You £30,000 Over 20 Years?
In the world of passive investing, fees are the silent killer of returns. A difference of just half a percentage point might seem trivial on a monthly statement, but over an investment lifetime, its corrosive effect is enormous. This is the « convenience tax » in its most potent form. The power of compounding works both for you and against you; just as your returns compound, so do the fees you pay, eating into your final portfolio value year after year.
To put this in perspective, consider the numbers. As investment fee calculators demonstrate, a £100,000 investment that generates a 4% annual return would be worth approximately £20,000 less after 20 years with a 0.5% annual fee compared to a no-fee scenario. The drag on performance is relentless and grows exponentially over time. This is why a laser focus on total cost is the hallmark of a savvy passive investor.
This cost becomes even more significant when you account for « fee stacking, » a common occurrence with robo-advisors. You don’t just pay one fee. You pay the robo-advisor’s platform management fee (e.g., 0.45%) on top of the underlying ETF’s own expense ratio (e.g., 0.22%). These small percentages combine to create a much larger drag on your growth. While the robo-advisor provides valuable services like rebalancing and behavioral coaching, you must be aware of the exact price you are paying for that convenience.
This visual representation shows how even small differences in fees can lead to vastly different outcomes over the long term due to the power of compounding.
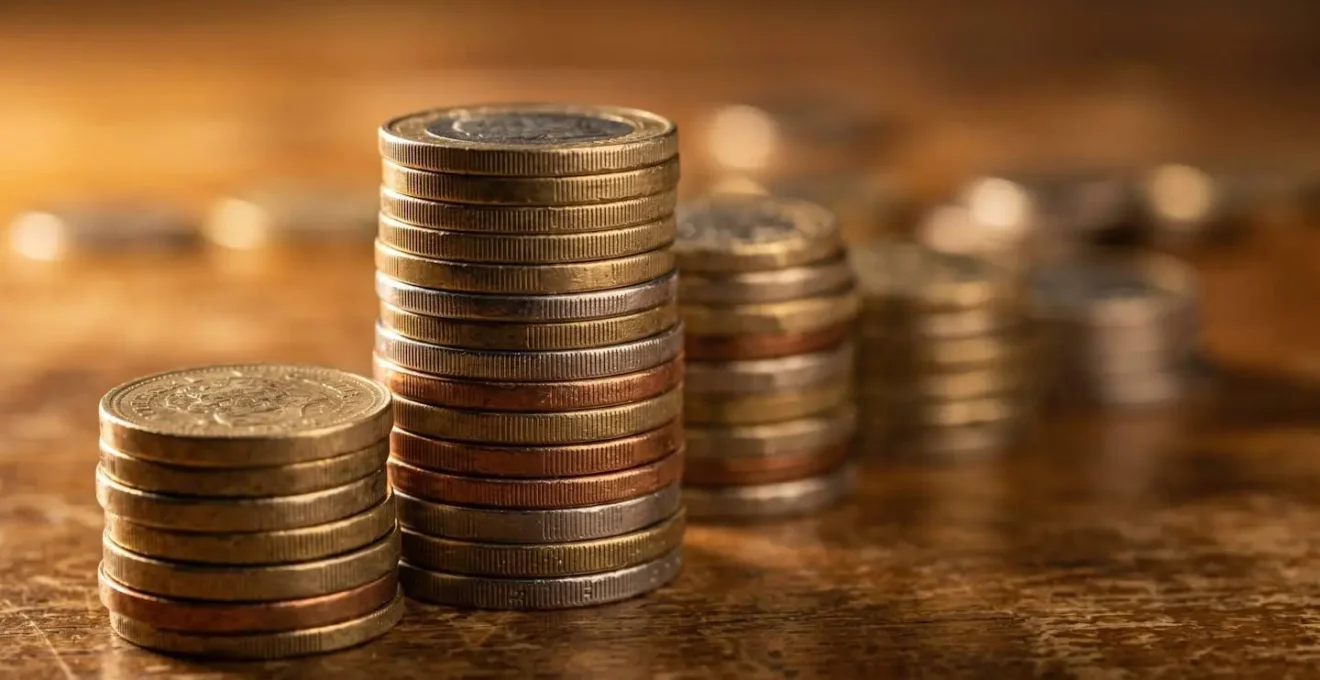
As the stacks of coins illustrate, the tallest column represents a portfolio with lower fees, allowing returns to compound more effectively. The shorter, out-of-focus stacks show how higher fees erode wealth, leaving you with a substantially smaller nest egg. This is the tangible cost of overlooking seemingly small percentages.
Case Study: The Real-World Impact of Fee Stacking
An analysis comparing total costs highlights the danger. An investor contributing £300 monthly for 30 years with an average 7% return would accumulate £355,191 with a total annual fee of 0.25%. However, if the total fee rises to 0.75%—a common scenario when combining platform and fund fees—the final pot shrinks to £318,144. That’s a staggering £37,047 difference, all lost to a seemingly tiny 0.5% fee differential. This illustrates how platform and fund fees (OCF) compound against investors, even when the individual percentages appear negligible.
The Synthetic ETF Trap That Adds Hidden Counterparty Risks to Your Savings
As you delve deeper into automating your ETF strategy, you’ll encounter two main types of ETFs: physical and synthetic. A physical ETF holds the actual underlying assets of the index it tracks. If it tracks the FTSE 100, it owns shares in all 100 companies. A synthetic ETF, however, does not. Instead, it enters into a derivative contract, typically a swap, with a counterparty (usually a large investment bank) who agrees to pay the ETF the return of the index. This structure can be cheaper and more efficient for tracking obscure or difficult-to-access markets.
However, this efficiency introduces a hidden danger: counterparty risk. You are no longer just exposed to market risk; you are now also exposed to the risk that the investment bank providing the swap could default. If the counterparty fails, the ETF could suffer significant losses. While you might own shares in the ETF, the fund itself doesn’t own the underlying assets—it owns a promise to be paid. This is a crucial distinction often missed by novice investors drawn to the lower expense ratios of some synthetic products.
To mitigate this, regulators have put strict rules in place. For ETFs sold in the UK and Europe, European regulatory frameworks (UCITS) mandate that the counterparty risk exposure in a synthetic ETF cannot exceed 10% of the fund’s Net Asset Value (NAV). The funds must also hold a basket of high-quality collateral to cover the exposure, which is re-evaluated daily. So, can you lose all your money? It’s highly unlikely, but the risk profile is undeniably different from a physical ETF. The trap isn’t that they are guaranteed to fail, but that they introduce a layer of financial complexity and risk that many investors are not aware they are taking on.
Academic Insight: Collateralisation in Synthetic ETFs
A detailed academic study published in the Journal of Banking & Finance analysed the collateral portfolios of BlackRock and db X-trackers’ ETFs. It found that, on average, synthetic ETFs were over-collateralised, holding assets worth 108.4% of their NAV. This collateral consisted of high-quality, diversified assets like large-cap equities and highly-rated government bonds. The research concluded that while counterparty risk is inherent to the structure, it is actively and effectively mitigated through these strict collateral management practices. Nevertheless, the study confirmed that synthetic ETFs still present a larger, more complex counterparty risk profile than physical ETFs, even those that engage in securities lending.
When Should You Move Your Tracking Portfolio From a Robo-Advisor to a DIY Broker?
Robo-advisors are exceptional « starter engines » for an automated investment journey. They provide discipline, diversification, and simplicity when you need it most. However, as your portfolio grows, the very feature that makes them attractive—a percentage-based fee for all-in-one management—becomes their biggest drawback. There is a clear financial tipping point where the « convenience tax » of a robo-advisor outweighs its benefits, making a switch to a low-cost DIY broker the logical next step.
This tipping point typically occurs when a portfolio reaches the £50,000 to £80,000 range. At this level, a 0.75% all-in fee (platform + fund) on an £80,000 portfolio costs £600 per year. In contrast, a DIY platform like Vanguard or Interactive Investor might charge a fixed fee or a capped percentage fee that amounts to significantly less. For example, Vanguard’s 0.15% platform fee is capped at £375 per year. The savings become more pronounced with larger portfolios, directly boosting your net returns. As recent surveys indicate that individuals using robo-advisors save 5-10 hours per month, the decision becomes a clear trade-off: is the time saved and convenience worth the escalating annual cost?
The move to a DIY broker is a graduation. It requires more knowledge—you’ll be responsible for choosing your own ETFs, rebalancing your portfolio, and managing your own trading behaviour. But it also unlocks greater control, flexibility to invest in a wider range of assets, and, most importantly, substantial cost savings that will compound significantly over the long term. The ‘automation’ doesn’t disappear; you simply take direct control of the engine.
The decision to switch is a strategic one, balancing cost against convenience. This table outlines the key differences to help you decide when you’re ready to graduate.
| Factor | Robo-Advisors | DIY Platforms |
|---|---|---|
| Control | Algorithm-managed, less control | Complete control over assets and timing |
| Cost Structure | 0.25% – 0.75% percentage-based fee | Fixed fees or lower % (often capped) |
| Optimal for Portfolio Size | Under £50,000 – £80,000 | Above £50,000 – £80,000 (fixed fees become cheaper) |
| Time Commitment | Minimal (5-10 hours saved/month) | Significant research & monitoring required |
| Expertise Required | Low – ready-made portfolios | High – need to understand risk assessment & rebalancing |
| Flexibility | Limited to platform’s fund selection | Access to stocks, ETFs, investment trusts, bonds |
| Tax Management | Basic ISA/SIPP wrappers | Advanced strategies (Bed & ISA, tax-loss harvesting) |
How to Automate Dividend Reinvestment to Accelerate Your Compound Growth?
One of the most powerful yet overlooked features of investment automation is handling dividends. When the companies within your ETF pay out dividends, you have a choice: take them as cash (Income or ‘INC’ funds) or automatically reinvest them to buy more of the fund (Accumulating or ‘ACC’ funds). For any long-term investor focused on growth, the choice is clear: automation through accumulating ETFs is non-negotiable. This simple selection dramatically accelerates compound growth.
Accumulating ETFs handle the entire reinvestment process internally. The fund manager collects the dividends and uses them to buy more underlying assets, causing the price of your ETF shares to rise. This is the most seamless form of automation. It happens before the money ever has a chance to hit your account, eliminating the temptation to spend it. It also avoids any potential broker fees for reinvesting and prevents « cash drag »—the loss of potential returns when dividends sit idly as cash in your account, waiting to be manually reinvested.
While most UK robo-advisors automatically reinvest dividends by default, it’s crucial to understand their specific policy. Some may reinvest instantly, while others might wait for dividends to reach a certain threshold, creating minor cash drag. When using a DIY platform, the responsibility is on you to actively choose the ‘ACC’ version of an ETF over the ‘INC’ version. This single choice when you buy the ETF sets up a powerful, self-perpetuating cycle of growth. This, combined with the auto-rebalancing that platforms offer, creates a truly hands-off compounding machine. According to platform operational standards, most UK robo-advisors regularly rebalance portfolios automatically to maintain agreed risk limits, further enhancing this automated discipline.
Checklist: Your Dividend Automation Audit
- Choose Accumulating (ACC) ETFs: When selecting funds, always prioritise the ‘ACC’ version over ‘INC’ to ensure dividends are reinvested automatically within the fund, maximising compounding and minimising fees.
- Verify Reinvestment Policy: Check your robo-advisor’s terms. Do they reinvest dividends instantly or wait for a minimum balance? Minimise any potential ‘cash drag’ from idle cash.
- Enable Automatic Rebalancing: Ensure your platform’s auto-rebalancing feature is active. This maintains your target asset allocation as dividends are reinvested, keeping your risk profile consistent without manual intervention.
- Understand Tax Implications: Within an ISA or SIPP, all reinvested dividends are tax-free. In a General Investment Account (GIA), ACC units simplify tax reporting by tracking ‘notional distributions’ for you.
- Monitor Cash Balance Quarterly: Briefly check your account each quarter to confirm that no cash from dividends is sitting uninvested, which would reduce your long-term compounding potential.
Hedged vs Unhedged Global ETFs: Which Protects Your Portfolio Better Today?
When you, as a UK investor, buy a global ETF that tracks the S&P 500 or a world index, you are making two bets: one on the performance of the underlying companies and another on the exchange rate between the US dollar (or other foreign currencies) and the British pound. If the pound strengthens against the dollar, the value of your US investments will fall when converted back into pounds. To mitigate this, some ETFs offer a « currency-hedged » version. These funds use financial instruments to neutralise the effect of currency fluctuations, ensuring your return is based purely on the asset’s performance.
This sounds like a prudent form of insurance, but it comes at a significant and guaranteed cost. The process of hedging isn’t free. As ETF cost analysis reveals that currency-hedged ETFs typically charge 0.30% to 0.75% or more in fees, which is substantially higher than their unhedged counterparts. This extra fee acts as a permanent drag on your performance. While hedging can protect you during periods of sterling strength, it also prevents you from benefiting when sterling weakens, which would otherwise boost your overseas returns.
For long-term passive investors with a time horizon of 20+ years, the academic consensus is that currency hedging is generally not worth the cost. Over multiple decades, currency fluctuations tend to even out. The persistent, higher fee of a hedged ETF, however, is a guaranteed loss. The protection it offers in the short term is often outweighed by the performance it surrenders in the long term. Therefore, for a truly passive, low-cost, automated strategy, sticking with unhedged global ETFs is typically the more prudent and profitable choice.
Case Study: The Guaranteed Cost of Currency Insurance
An analysis of ETF expense ratios shows that the additional cost of hedging is substantial. For a UK investor with a £50,000 global equity portfolio, an extra 0.30% hedging premium translates to a direct cost of £150 every single year. Over a 20-year investment horizon, that small fee alone, even without considering lost returns, adds up to thousands of pounds. Since long-term currency movements are notoriously difficult to predict and tend to revert to the mean, paying this guaranteed annual premium for an unguaranteed benefit is a poor trade-off for the disciplined, long-term investor.
Key takeaways
- Robo-advisors are powerful « behavioral discipline engines, » ideal for starting your investment journey and for managing portfolios under the £50,000 mark.
- The « convenience tax » of percentage-based fees makes DIY platforms with capped or fixed fees significantly cheaper for larger portfolios, boosting your net returns.
- True automation requires attention to detail: choosing accumulating (ACC) over income (INC) ETFs and typically avoiding costly currency-hedged funds are crucial for maximising compound growth.
How to Configure Automated Trading Bots for Consistent Passive Income?
The term « automation » in finance often conjures images of high-frequency trading bots executing thousands of trades per day to scalp tiny profits. This is a world of complex algorithms, high risk, and constant monitoring. It’s crucial to understand that the automation offered by a UK robo-advisor is the philosophical opposite of this. Confusing the two can lead to disastrous investment decisions.
Crypto trading bots, such as those using grid or DCA (Dollar Cost Averaging) strategies, are designed to capitalise on short-term volatility. They aim to generate active income through rapid-fire transactions. A robo-advisor, in stark contrast, is a sophisticated, low-frequency automation engine programmed with the principles of Modern Portfolio Theory. Its primary function is not to trade, but to enforce long-term behavioural discipline. Its « algorithm » is designed to perform a few key actions exceptionally well over a 5+ year horizon: maintain a target asset allocation, reinvest dividends, and, most importantly, prevent the investor from panic selling during market downturns.
The « passive income » from a robo-advisor comes from the long-term, slow-and-steady growth of global markets, not from tactical trading. It is automation in service of strategy, not speculation. As the analysis from FinTech Observe highlights, the realism of the robo-advisor model is its core strength for the average person.
Robo-advisors are not superior by default, but they are often more realistic for people who want consistent, long-term investing without constant involvement.
– FinTech Observe Analysis, Robo-Advisors in the UK & Europe
Case Study: Robo-Advisors as Low-Frequency Behavioral Bots
The fundamental distinction lies in philosophy. A crypto bot might perform well in a sideways market but can suffer catastrophic losses during a strong, sustained trend. In contrast, a robo-advisor like Moneyfarm or InvestEngine is programmed for strategic patience. Its automated rebalancing, which may only occur quarterly or annually, is not a market-timing tool. It is a risk-management action to bring the portfolio back to its original target allocation. The « automation » in a UK robo-advisor is therefore a mechanism designed to protect investors from their worst behavioral impulses, prioritising discipline over the illusion of tactical advantage.
Now that you understand the full automation spectrum, from hands-off robo-advisors to DIY platforms, the next step is to assess your current portfolio size, time commitment, and financial knowledge. Use this guide’s frameworks to determine which type of automation engine is the most cost-effective and suitable solution for you today, while planning for your financial future.